
Blogs
PW Consulting: Borehole Camera Market Hits USD 198.75 Million in 2025, Growing at 5.85% CAGR
By pmarketresearch, 2026-09-16
Navigating the Subsurface: Strategic Insights for the 2026 Borehole Camera Market
In an era where subsurface intelligence dictates operational safety, regulatory compliance, and capital efficiency, the borehole camera sector has evolved from a niche inspection tool into a critical infrastructure enabler. As organizations across energy, environmental services, and civil engineering confront stricter oversight and deeper technical demands, understanding the trajectory of this market is no longer optional—it is a strategic imperative. This executive briefing introduces a comprehensive market research publication designed to equip decision-makers with actionable intelligence for the 2026–2032 horizon. By synthesizing historical performance, forward-looking projections, and competitive dynamics, the study delivers the clarity needed to navigate an increasingly complex landscape.
Why 2026 Marks a Decisive Inflection Point
The borehole camera industry has demonstrated resilient expansion over the past half-decade, driven by aging infrastructure mandates, intensified environmental auditing, and the growing reliance on precision downhole imaging. Recent historical tracking reveals a steady upward trajectory, with total market value climbing from approximately $142.35 million in 2020 to an estimated $198.75 million in 2025. This pattern reflects sustained procurement activity across both established industrial corridors and emerging assessment markets. Looking ahead, the forecast period through 2032 outlines a compound annual growth rate of 5.85 percent, positioning the sector for continued investment and technological maturation. While year-over-year fluctuations may occur, the underlying momentum remains anchored in structural demand rather than transient trends. For corporate strategists, this growth curve signals a window to align product roadmaps, service offerings, and regional deployment strategies with the cadence of market expansion.
Deconstructing the Research: What Decision-Makers Will Gain
A rigorous analysis requires more than headline figures. The full study dissects the industry through multiple operational lenses, enabling stakeholders to translate macro trends into executable plans. Key architectural components of the publication include:
- Segmentation Architecture: A granular breakdown of product categories and application domains, revealing where imaging technologies are gaining traction and how performance specifications are evolving to meet field requirements.
- Macro Demand Mapping: Cross-referencing historical procurement cycles with projected adoption curves, allowing procurement and engineering leaders to anticipate inventory needs, service capacity, and integration timelines.
- Competitive Intelligence Framework: Detailed profiles of established manufacturers and emerging entrants, accompanied by an evaluation of recent strategic maneuvers, partnership activity, and technological differentiation.
- Regulatory and Compliance Overlay: An examination of how environmental assessment mandates, well-sealing protocols, and subsurface documentation requirements are shaping inspection workflows and camera specification preferences.
- Scenario Modeling: Forward-looking projections that account for technological adoption rates, supply chain considerations, and regional deployment patterns, providing a structured approach to capital allocation and market entry planning.
Each section is engineered to answer the questions that keep operations directors, product managers, and investment committees awake at night: Where should resources be concentrated? Which capabilities will separate market leaders from followers? How do regulatory shifts reshape procurement priorities?
Competitive Dynamics and Strategic Positioning
The market landscape is characterized by a mix of legacy specialist firms, region-focused manufacturers, and technology-driven entrants that are redefining inspection capabilities. Market concentration metrics indicate that the top three players collectively command an estimated 38.5 percent share, while the top five control approximately 52.7 percent. This distribution suggests a moderately consolidated environment where scale, brand trust, and specialized engineering expertise provide measurable advantages, yet sufficient fragmentation remains for agile competitors to carve out differentiated positions through innovation or localized service networks.
Borehole Camera Market
Several established organizations illustrate the strategic diversity shaping the sector. Laval Underground Surveys, with over seven decades of operational heritage, has long positioned itself as a pioneer in borehole and water well camera systems, offering a spectrum of portable, skid-mounted, and vehicle-integrated platforms engineered for depths extending thousands of feet. Its enduring focus on groundwater and geotechnical inspections underscores a strategy built on durability, field reliability, and domain-specific expertise. In parallel, Allegheny Instruments has cultivated a reputation for customizable imaging solutions, notably through its GeoVISION line of borehole video systems. From compact Nano-format units designed for restricted access to dual-scan and pan-tilt configurations rated for substantial submergence, the company’s approach centers on adaptability across water wells, monitoring wells, geotechnical borings, and mine shafts.
Geographic and technological diversification further complicates the competitive picture. Chongqing Gold Mechanical & Electrical Equipment Co., Ltd. has expanded its footprint as a Chinese manufacturer of borehole inspection cameras, water well systems, and geophysical tooling, introducing 360-degree rotary HD platforms capable of operating across a broad depth range for well inspection and geological logging. Meanwhile, Well-Vu has differentiated itself through digital underwater inspection cameras and waterproof consoles that integrate on-screen parameters such as total dissolved solids and temperature, reflecting an industry-wide push toward streamlined data capture during field assessments. Deep Trekker Inc. adds another dimension by leveraging robotic and underwater system architectures adaptable to borehole and cavity inspections, deploying high-resolution imaging to address complex subsurface conditions where traditional push-cable systems encounter operational limits.
Strategic activity over the recent period reinforces the intensity of competition. In mid-2023, Laval Underground Surveys executed an acquisition that absorbed a leading competitor’s water well camera division, a move widely interpreted as consolidating its position as a dominant global supplier in that segment. More recently, in late 2024, Chongqing Gold showcased its borehole camera and geophysical equipment capabilities at a major U.S. exhibition, signaling an intent to deepen cross-border engagement and visibility among North American procurement networks. Such developments illustrate that market leadership is increasingly determined not only by product specifications but also by strategic consolidation, geographic outreach, and the ability to align technological portfolios with evolving field requirements.
Regulatory Pressures and Operational Realities
The trajectory of borehole camera adoption cannot be disentangled from the regulatory and operational frameworks that govern subsurface work. Environmental and groundwater assessment practices increasingly rely on borehole video cameras to provide in-situ depiction of visible features along the interior walls of air- or water-filled boreholes, effectively standardizing visual verification as part of site characterization and compliance documentation. Such practices elevate camera systems from supplementary tools to integral components of audit-ready workflows. At the same time, jurisdictional requirements continue to evolve. For instance, guidance surrounding the sealing of abandoned wells and boreholes emphasizes the necessity of proper documentation and may reference downhole camera inspections to verify subsurface conditions prior to closure. These mandates have direct implications for procurement cycles, inspection protocols, and the specification of imaging systems capable of capturing defensible, high-quality visual records.
Beyond compliance, operational realities are reshaping equipment expectations. Field technicians require systems that balance portability with depth capability, image fidelity with environmental resilience, and real-time readability with data storage integrity. As inspection scopes expand to encompass complex lithological conditions, confined well structures, and multi-parameter monitoring, the market is witnessing a gradual shift toward integrated imaging solutions that reduce manual interpretation overhead and support faster decision-making. Organizations that recognize this shift early are better positioned to influence specification standards, secure recurring service engagements, and build long-term relationships with end-user communities.
Sewer Cameras Market
How to Translate Intelligence into Action
Market research achieves its highest return when it bridges analysis and execution. The full publication is structured to support a range of strategic applications. Product and engineering teams can use segmentation insights to prioritize feature development, identify performance thresholds that matter most to end users, and avoid over-investment in specifications with limited field demand. Commercial and sales leadership can leverage competitive profiling and regional demand indicators to refine targeting, tailor messaging, and anticipate where procurement budgets are likely to expand. Procurement and operations managers can reference compliance overlays and inspection workflow analysis to align equipment selection with documentation requirements and reduce rework caused by inadequate imaging. For investors and corporate development teams, the concentration metrics and recent strategic transactions offer context for evaluating partnership opportunities, acquisition targets, and market entry timing.
The study deliberately preserves the analytical discipline required for high-stakes planning: it presents the structural forces, the competitive contours, and the demand signals without diluting them into oversimplified narratives. This approach ensures that readers encounter the depth necessary to challenge assumptions, stress-test strategies, and build scenarios grounded in evidence rather than extrapolation alone.
What the Full Study Covers
To convert early awareness into informed action, the complete research package delivers a systematically assembled view of the borehole camera ecosystem. It integrates historical performance data, forecast modeling, segmentation analysis, competitive profiles, and regulatory context into a single reference architecture. Decision-makers will find detailed discussion of imaging technology evolution, application-specific adoption patterns, the influence of inspection protocols on equipment selection, and the strategic implications of recent corporate activity. Equally important, the publication is designed to be consultative: it frames findings in a manner that supports scenario planning, investment prioritization, and operational alignment across multiple stakeholder groups.
Positioning for the Next Phase of Growth
The borehole camera market sits at the intersection of infrastructure stewardship, environmental accountability, and imaging technology maturation. As subsurface assessments grow more rigorous and documentation expectations tighten, organizations that combine technical credibility with strategic foresight will capture disproportionate value. The 5.85 percent projected compound annual growth rate through the forecast horizon is not merely a statistic; it reflects a sustained reorientation toward data-rich inspection practices that reduce uncertainty, accelerate approvals, and support safer operations. For executives preparing for 2026 and beyond, the practical question is no longer whether the market will expand, but how deliberately they will align their capabilities with the forces shaping that expansion.
Secure the Complete Intelligence
This executive overview has highlighted the structural drivers, competitive currents, and operational imperatives defining the borehole camera sector. Yet the most consequential details reside in the full research document, where segmentation depth, company-level analysis, and forecast architecture are presented with the precision required for executive planning. For organizations seeking to validate strategic assumptions, prioritize capital deployment, or understand where competitive advantage will be earned, the complete study provides the framework to move from awareness to execution. We invite decision-makers to access the full report and equip their teams with the market intelligence necessary to navigate the next phase of subsurface imaging evolution with confidence.
For detailed analysis of this topic, please visit the official page: Borehole Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Angiopoietin 2 Market to Hit $8,041.41M by 2032, 12.85% CAGR
By pmarketresearch, 2026-09-16
The Angiopoietin 2 Market: Strategic Imperatives and Growth Trajectories Through 2032
The therapeutic and diagnostic landscape surrounding Angiopoietin 2 is undergoing a structural transformation that demands immediate executive attention. Over the past half-decade, the market has transitioned from a niche research domain into a commercially significant segment driven by dual-pathway vascular targeting, expanding retinal indications, and a maturing pipeline of bispecific modalities. For corporate strategists, portfolio managers, and investment committees, the current inflection point represents both a valuation opportunity and a competitive risk. Understanding where capital is flowing, which mechanisms are gaining clinical traction, and how regulatory pathways are shifting will define market positioning through the end of the decade.
This analysis draws from comprehensive forecasting models that map historical consolidation against forward-looking demand signals. The data reveals a sector that has moved beyond experimental validation into commercialization scaling, with clear implications for drug development, diagnostic manufacturing, reimbursement strategy, and competitive positioning. What follows is a disciplined examination of the forces shaping the Angiopoietin 2 ecosystem, designed to equip decision-makers with the structural clarity required to allocate resources, time market entry, and anticipate displacement dynamics.
Macro Trajectory: From Validation to Commercial Scaling
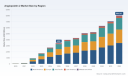
Historical revenue patterns across the 2020 to 2025 window illustrate a market that has accelerated decisively once clinical and commercial proof points aligned. Early baseline activity gave way to a pronounced expansion phase as dual-inhibition strategies demonstrated differentiated efficacy in retinal vascular disease, while parallel diagnostic demand matured around standardized quantification workflows. By the 2025 base year, the market had reached a consolidated valuation of approximately 3,450 million USD, reflecting both therapeutic uptake and robust research-grade tooling adoption.
Forward projections indicate sustained momentum rather than a transient peak. The forecast horizon through 2032 models a compound annual growth rate of 12.85 percent, culminating in a market valuation that meaningfully expands the commercial ceiling for both branded therapeutics and supporting research infrastructure. This trajectory is not uniformly distributed across time; it is shaped by label expansions, dosing flexibility adoption, regional access dynamics, and the maturation of next-generation molecular formats. For executives, the critical implication is that growth is structurally embedded in the mechanism of action rather than dependent on isolated product cycles.
The growth curve also reflects a market that is consolidating around higher-value interventions. Revenue concentration signals a landscape where a limited set of commercially advanced assets and diagnostic platforms command disproportionate share, reinforcing the need for precise competitive mapping. Organizations entering or expanding within this space must account for both the velocity of adoption and the barrier created by established dual-pathway franchises.
Segmentation Architecture: Where Value Is Concentrated
The Angiopoietin 2 market does not grow as a monolith. Its expansion is distributed across therapeutic indications, molecular formats, and geographic demand centers, each with distinct adoption drivers and commercialization requirements. Understanding these structural layers is essential for product planning, pricing strategy, and go-to-market sequencing.
Therapeutic Indications: Retinal Disease Dominance and Adjacent Expansion
Retinal vascular disease remains the principal demand engine. Neovascular AMD and diabetic macular edema together anchor the majority of therapeutic revenue, driven by high prevalence, recurrent treatment cycles, and the clinical advantage of addressing vascular instability through dual-pathway modulation. The revenue distribution across these indications underscores a market where retinal specialists are increasingly comfortable with flexible dosing paradigms that reduce treatment burden while preserving efficacy.
Beyond retinal disease, oncology and other inflammatory disorders represent a strategically important but structurally distinct segment. Here, the value proposition shifts from chronic vascular stabilization to tumor microenvironment modulation and combination immunotherapy sequencing. The commercial opportunity in this adjacent segment is contingent on clinical differentiation, biomarker enrichment, and reimbursement adjudication for combination regimens. For developers, this indicates a bifurcated strategy: optimize retinal uptake through dosing and access, while building oncology evidence through targeted trial design and partnership structures.
Drug Class Dynamics: The Bispecific Ascendancy
Molecular format is a defining axis of market value. Bispecific antibodies have emerged as the dominant commercial class, reflecting their ability to simultaneously neutralize VEGF-A and Angiopoietin 2 within a single molecular architecture. This design directly addresses the clinical rationale of combined vascular pathway inhibition, supporting both efficacy and dosing flexibility in practice. The revenue weighting toward bispecific formats signals that the market is rewarding mechanism convergence rather than incremental monotherapy optimization.
Monoclonal antibodies and small molecule inhibitors occupy more specialized positions within the landscape. Monoclonal approaches remain relevant where established manufacturing, regulatory familiarity, or combination logic favor single-target precision. Small molecule inhibitors serve differentiated niches, particularly in settings where oral administration, cost structure, or specific biomarker profiles create selective demand. The stratification across drug classes indicates that future competition will hinge not merely on target engagement but on format-level differentiation in pharmacokinetics, dosing convenience, manufacturing economics, and clinical positioning.
Geographic Demand Architecture
Regional demand patterns reveal a market shaped by healthcare infrastructure maturity, specialty physician density, reimbursement frameworks, and access to advanced retinal and oncology care. North America accounts for the largest revenue contribution, reflecting the concentration of high-value retinal practices, early adoption of flexible dosing regimens, and robust commercial infrastructure for novel biologics. Europe follows as a substantial demand center, supported by differentiated access pathways and strong clinical adoption in retinal disease management.
Asia Pacific represents a structurally important growth vector. The region’s expanding patient populations, growing specialty care networks, and increasing penetration of advanced diagnostics create a multi-layered demand environment. Latin America and the Middle East and Africa contribute more modest shares today but function as incremental growth markets where access expansion, pricing strategy, and diagnostic availability will determine the pace of adoption. For global strategists, regional planning must account for differing reimbursement rhythms, competitive entry timing, and the diagnostic ecosystem that supports both research and clinical quantification workflows.
Competitive Landscape: Differentiated Positioning Around a Dual-Pathway Core
The competitive structure of the Angiopoietin 2 market is characterized by clear stratification between therapeutic innovators, diagnostic and research tool providers, and organizations operating at the intersection of both. Market concentration indicates that a small cohort of commercially advanced players commands a dominant share of therapeutic value, while a broader ecosystem of research suppliers supports the scientific and clinical infrastructure underlying biomarker quantification and drug development.
F. Hoffmann-La Roche Ltd, through its Genentech portfolio, anchors the therapeutic side of the market with faricimab, a bispecific antibody designed to inhibit both VEGF-A and Angiopoietin 2. The strategic importance of this asset extends beyond its current label footprint. Recent regulatory expansion into macular edema secondary to retinal vein occlusion, alongside product format innovations such as prefilled syringe availability, reflects a deliberate effort to broaden usability, reduce administration friction, and extend real-world adoption. The dual-pathway mechanism supports flexible dosing regimens that address a persistent clinical pain point in retinal care, reinforcing the asset’s positioning as a therapy built for chronic management rather than episodic intervention.
Boehringer Ingelheim represents a distinct competitive vector through its development of BI 836880, a bispecific nanobody targeting VEGF and Angiopoietin 2 in clinical evaluation for solid tumors. This approach illustrates how Angiopoietin 2 targeting is being translated into oncology combination strategies, where nanobody architecture, tumor microenvironment engagement, and immuno-oncology pairing may create differentiated value. The publication of early-phase clinical data signals a pipeline that is actively exploring the boundaries of the mechanism beyond retinal disease.
On the research and diagnostic side, a parallel competitive field has formed around reliable quantification and reproducible assay infrastructure. R&D Systems, Abcam, Thermo Fisher Scientific, Sigma-Aldrich, and Sino Biological each contribute to a market ecosystem that depends on consistent biomarker measurement across serum, plasma, cell culture supernates, and other sample types. ELISA kits, recombinant proteins, and antibody reagents form the backbone of both drug development workflows and clinical research operations. In this segment, competition is driven by assay robustness, sample versatility, supply reliability, and the ability to navigate raw material price volatility in bioreagents. As global demand and manufacturing constraints continue to influence input costs, suppliers that can maintain consistency and scale will consolidate advantage in the research tooling layer.
The broader implication for strategists is that the Angiopoietin 2 market is not a single competitive arena but a linked system. Therapeutic adoption reinforces diagnostic and research demand; diagnostic reliability supports clinical evidence generation; and evidence generation, in turn, shapes regulatory and reimbursement trajectories. Organizations that understand these interdependencies are better positioned to anticipate downstream effects of product launches, label expansions, and pipeline readouts.
Worldwide INF2 Antibody Market
Market Dynamics: Regulation, Reimbursement, and Input-Side Pressure
Several structural dynamics are reshaping how value is created and captured in this market. Regulatory breadth is expanding the addressable patient population. Faricimab has already achieved approval across more than 100 countries for neovascular AMD and diabetic macular edema, and across more than 30 countries for macular edema following retinal vein occlusion. This global regulatory footprint reduces market fragmentation risk for the leading dual-pathway asset and establishes a high bar for entrants seeking comparable geographic coverage.
Reimbursement dynamics are increasingly intertwined with clinical convenience. Angiopoietin 2 inhibitors that target dual pathways and support flexible dosing regimens create value not only through efficacy but through treatment burden reduction. In practice, flexible dosing can influence adherence, clinic throughput, and total cost of care, making reimbursement adjudication sensitive to real-world administration patterns as well as clinical endpoints. For commercial teams, this means that access strategy must be built around dosing flexibility, site of care considerations, and the economic logic of chronic management.
On the supply side, raw material volatility presents an ongoing operational consideration. ELISA kit production and broader bioreagent manufacturing face price pressure linked to global demand and manufacturing constraints. This dynamic affects both diagnostic suppliers and drug developers who rely on consistent reagent quality for assay development, biomarker quantification, and quality control workflows. Organizations that embed supply resilience, dual sourcing, and inventory agility into their operating models will be better insulated from input-side disruption.
Strategic Implications for 2026 Decision-Making
For executives evaluating exposure to the Angiopoietin 2 market in 2026, the strategic question is no longer whether the mechanism has clinical relevance. That question has been answered by regulatory approvals, commercial uptake, and expanding indication coverage. The decisive questions now concern sequencing, differentiation, and ecosystem positioning.
First, therapeutic entrants must assess whether they can compete on dual-pathway convenience, dosing architecture, and regional access, or whether they should pursue differentiated niches in oncology, inflammatory disease, or combination regimens. The revenue concentration in the market suggests that broad retinal uptake will be contested by established bispecific franchises, while adjacent indications may offer more targeted entry points for developers with distinct molecular formats or partnership advantages.
Second, diagnostic and research suppliers should treat biomarker quantification infrastructure as a strategic layer rather than a commoditized support function. Demand for reliable Angiopoietin 2 measurement will remain tightly coupled to drug development activity, clinical research, and real-world evidence generation. Competitive advantage will accrue to suppliers that can deliver reproducible performance across sample types while managing input volatility and scaling efficiently.
Third, market participants should plan around the interaction between regulatory expansion, reimbursement logic, and regional adoption. A global approval footprint accelerates market maturity in leading regions, but incremental indications and format innovations can reshape local demand curves. Strategic planning should therefore incorporate both the timing of label changes and the practical economics of administration, site of care, and access negotiation.
Angiopoietin 2 Market
What the Full Study Provides
This article outlines the structural logic of the Angiopoietin 2 market and the strategic questions that matter for 2026 planning. The full market research study extends this framework into a detailed, decision-ready intelligence package. It provides granular market sizing across the forecast window, segmentation analysis by region, indication, and drug class, and a competitive profile set that maps product positioning, development activity, and recent commercial and regulatory milestones. The study also examines market concentration, dynamic drivers across regulation, reimbursement, and raw material supply, and the interaction between therapeutic adoption and diagnostic demand.
For teams that need to convert market awareness into actionable strategy, the complete report offers the depth required to support portfolio prioritization, entry timing, pricing and access design, and competitive response planning. The macro trajectory, segmentation architecture, and competitive dynamics described here are intended to establish the analytical foundation; the full study delivers the operational specificity necessary to move from direction to execution.
The Angiopoietin 2 market is advancing along a structurally strong growth path, supported by dual-pathway clinical rationale, expanding regulatory coverage, and a competitive field that spans both therapeutics and research infrastructure. Organizations that analyze this landscape with precision will be better equipped to capture value, manage risk, and position for the next phase of commercialization through 2032.
For detailed analysis of this topic, please visit the official page: Angiopoietin 2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global 2-Cyanobenzyl Bromide Market Hits $50.8M in 2025, Growing at 5.82% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence Report: Navigating the Global 2-Cyanobenzyl Bromide Market (2026–2032)
Executive Summary: The Strategic Imperative for 2026
The global chemical supply chain is entering a phase of renewed complexity in 2026. For strategic decision-makers in the pharmaceutical and fine chemical sectors, understanding the trajectory of key intermediates is no longer optional; it is a critical component of risk management and growth planning. Our latest Worldwide 2-Cyanobenzyl Bromide Market research provides a comprehensive lens into this specialized yet vital segment. As organizations align their portfolios for the forecast period extending to 2032, the data reveals a market characterized by steady expansion, regional concentration, and evolving regulatory frameworks that demand agile sourcing strategies.
Worldwide 4-Brombenzonitrile Market
This report is designed to move beyond surface-level observations. It offers a granular decomposition of the market forces shaping the demand and supply of 2-Cyanobenzyl Bromide (CAS 22115-41-9). With a historical trajectory showing consistent growth from 2020 through 2025 and a projected Compound Annual Growth Rate (CAGR) of 5.82% during the forecast period, the compound presents a stable yet opportunity-rich environment for stakeholders. The base year analysis of 2025 establishes a robust foundation, indicating that the market has successfully weathered recent supply chain volatility to establish a new equilibrium point valued at approximately USD 50.8 Million. Understanding the dynamics behind this number is essential for capitalizing on the upward trend anticipated through 2032.
Market Trajectory and Growth Dynamics
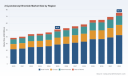
The historical performance of the 2-Cyanobenzyl Bromide market underscores a resilient demand structure. Between 2020 and 2025, the market demonstrated a clear upward trajectory, moving from initial valuations to a significant baseline in 2025. This growth is not merely nominal; it reflects sustained procurement by downstream industries that rely on this intermediate for critical synthesis processes. The forecast period from 2026 to 2032 suggests continued momentum, with revenue projections indicating a steady climb toward the end of the decade.
Worldwide 2-Cyanobenzyl Bromide Market
Strategic planners must note that this growth is underpinned by specific industrial drivers rather than speculative hype. The compound serves as a pivotal building block in the synthesis of various active pharmaceutical ingredients (APIs) and agrochemical products. As global health initiatives expand and agricultural productivity demands increase, the consumption of high-quality intermediates correlates directly with these macro trends. However, the rate of growth is moderated by production complexities and regulatory compliance costs, creating a balanced market environment where supply chain efficiency becomes a key differentiator for suppliers and buyers alike.
Segmentation and Structural Complexity
A deep understanding of market segmentation is crucial for targeted strategy formulation. The market is not a monolith; it is divided by distinct purity grades and application silos that dictate pricing power and supply reliability. Our analysis dissects these segments to reveal where value is concentrated and where vulnerabilities may lie.
Purity Grade Dynamics
The market is primarily segmented by purity, specifically distinguishing between the 98% Purity Grade and the Above 99% Purity Grade. This distinction is more than chemical semantics; it represents different market tiers. The higher purity segment caters to sensitive pharmaceutical synthesis where impurity profiles can impact regulatory approval and product efficacy. Suppliers capable of consistently delivering above 99% purity often command premium positioning, particularly when supporting the synthesis of complex APIs. Conversely, the 98% grade remains relevant for broader industrial applications and research contexts where absolute purity thresholds are slightly more flexible. Navigating the trade-offs between cost and purity specifications is a daily challenge for procurement teams, and our report provides the framework to optimize these decisions based on end-use requirements.
Application Verticals
Demand is diversified across key application areas, with Pharmaceutical Intermediates representing the dominant consumption driver. This vertical absorbs the largest share of production, driven by the ongoing development of new drug formulations and the manufacturing of established medications such as Alogliptin, where the compound serves as a specific intermediate. Beyond pharmaceuticals, the Agrochemical Synthesis sector contributes to demand, reflecting the need for specialized chemicals in crop protection and enhancement. Additionally, Laboratory and Research activities maintain a steady baseline of consumption, supporting R&D pipelines that may eventually transition into commercial scale production. Understanding the proportion of demand attributed to each vertical allows companies to anticipate shifts in procurement patterns should R&D priorities or regulatory landscapes change.
Regional Distribution
Geographically, the market exhibits distinct concentration patterns. Asia Pacific stands out as a significant hub for production and consumption, reflecting the region's robust chemical manufacturing infrastructure and growing domestic demand. Europe and North America represent mature markets with stringent regulatory environments that influence sourcing decisions. The Rest of World segment, while smaller, represents emerging opportunities for market expansion. Regional dynamics are heavily influenced by local manufacturing capabilities, logistics networks, and specific regulatory compliance requirements such as REACH in Europe versus TSCA considerations in the United States. Companies operating across borders must tailor their risk assessments to these regional variances to ensure uninterrupted supply.
Competitive Landscape and Key Players
The market structure is moderately concentrated, with the top three companies holding a combined share of approximately 45.5% and the top five entities commanding around 62.3% of the market. This concentration suggests that while there is room for niche players, a significant portion of supply stability rests with established manufacturers who have invested in capacity and compliance. Understanding the positioning of these key players is vital for negotiation strategies and supply chain diversification.
Key Manufacturers and Suppliers
- Lianyungang Qunsheng Chemical Co., Ltd. : Based in Jiangsu Province, China, this active manufacturer lists production and supply capabilities for the global market, positioning itself as a direct source for pharmaceutical intermediates.
- Changzhou Wujin Minghuang Chemical Co., Ltd. : Located in Changzhou, this producer specializes in coal tar series chemicals and manufactures the compound for supply as a chemical intermediate, leveraging specific raw material access.
- Zhejiang Shengyu Chemical : Operating in Zhejiang Province, this manufacturer supplies the compound for both pharmaceutical and agrochemical synthesis applications, indicating a diversified demand base.
- Shanghai Ruifu Chemical Co., Ltd. : This Shanghai-based manufacturer offers high-purity material (>99.0% HPLC) specifically as an intermediate in Alogliptin synthesis and other pharmaceutical APIs, highlighting a focus on therapeutic grade quality.
- Tokyo Chemical Industry Co., Ltd. (TCI) : With headquarters in Tokyo and global operations including TCI America, this supplier focuses on research-grade material (>98.0% GC purity) available in catalog quantities with bulk options, serving the organic synthesis and laboratory sector.
- Sigma-Aldrich (Merck KGaA) : As a global distributor based in Darmstadt, Germany, this entity supplies the compound for laboratory and research use in chemical synthesis, emphasizing distribution reach and brand trust in the scientific community.
- Capot Chemical Co., Ltd. : An active fine chemical manufacturer in Hangzhou, Zhejiang, with an extensive product list including this intermediate for pharmaceutical applications.
- Jinan Finer Chemical Co., Ltd. : Based in Jinan, this supplier offers the compound at 99% purity with significant supply capacity, indicating readiness for larger volume orders.
- Clearsynth : Operating from India with global export capabilities, this manufacturer and exporter focuses on high-quality material with CAS 22115-41-9, providing an alternative sourcing node outside of China.
- BLD Pharm : Based in China, this supplier provides the compound with supporting analytical data (NMR, HPLC, etc.), catering to research and synthesis needs where documentation is critical.
The presence of both large-scale distributors and specialized manufacturers creates a dynamic ecosystem. Buyers must evaluate suppliers not just on price, but on their ability to provide consistent quality, regulatory documentation, and supply continuity. The concentration of market share among the top players also implies that disruptions affecting these key entities could have ripple effects across the global supply chain.
Industry Dynamics: Feedstock, Regulation, and Compliance
Operational success in this market requires navigating a complex web of input costs and regulatory obligations. Two critical dynamics shape the current landscape in 2026.
Feedstock Cost Sensitivity
Production economics are sensitive to the pricing of key raw materials, particularly bromine. In January 2026, bromine prices in China averaged approximately USD 5443/MT FOB. As bromine serves as a key feedstock input for the bromination steps in 2-Cyanobenzyl Bromide production, fluctuations in this commodity price directly impact manufacturing margins and, consequently, supply pricing. Strategic planners must monitor these feedstock trends to forecast cost pressures and negotiate contracts that account for raw material volatility.
Regulatory Frameworks
Compliance is a non-negotiable aspect of handling and trading this chemical. Under the REACH Regulation (EC) No 1907/2006, 2-Cyanobenzyl Bromide is classified with skin corrosion/irritation hazards (Category 1A/B/C, H314). This classification necessitates specific handling and storage protocols, influencing logistics costs and safety requirements for warehouses and transport. Furthermore, regulatory status varies by jurisdiction. While the compound is noted as not listed on the EPA Toxic Substances Control Act (TSCA) inventory in multiple supplier safety data sheets, it remains designated for research use only or as a chemical intermediate in pharmaceutical synthesis. It is not intended for direct diagnostic or therapeutic use. These distinctions are critical for ensuring that end-use applications remain compliant with local laws and safety standards. Failure to adhere to these classifications can result in significant legal and operational risks.
Operational Deep Dive: Inside the Report
To support the strategic insights outlined above, our Worldwide 2-Cyanobenzyl Bromide Market research provides an extensive operational toolkit. The report is structured to facilitate immediate application of findings in business planning and investment decision-making.
- Historical and Forecast Data Series : Access detailed revenue data from 2020 through 2032, allowing for trend analysis and projection modeling. The data covers the base year 2025 and extends through the forecast period, providing a long-term view for capital allocation.
- Segmentation Analysis : Comprehensive breakdowns by Region, Type, and Application. This allows stakeholders to isolate growth pockets and assess the health of specific market verticals without getting lost in aggregate numbers.
- Competitive Company Profiles : In-depth profiles of key market participants, including their headquarters, operational focus, and supply capabilities. This section helps identify potential partners, competitors, or acquisition targets.
- Regulatory and Safety Context : Detailed documentation of safety data sheet requirements, hazard classifications, and regulatory statuses across key regions. This supports compliance teams in maintaining adherence to global standards.
- Strategic Recommendations : Actionable insights derived from the synthesis of market data, competitor analysis, and macroeconomic factors. These recommendations are tailored to help organizations optimize their supply chains and market positioning.
Conclusion: Positioning for Success in a Evolving Market
The 2026 landscape for 2-Cyanobenzyl Bromide offers a mix of stability and opportunity. With a projected CAGR of 5.82% through 2032 and a market size expected to grow from the 2025 baseline toward over USD 75 Million by the end of the forecast period, the aggregate picture is positive. However, aggregate growth masks the nuances of purity requirements, regional restrictions, and feedstock cost volatility.
Success in this market requires more than passive observation; it demands active management of supplier relationships, rigorous compliance adherence, and a clear understanding of where demand is originating. Whether you are a manufacturer looking to optimize capacity, a distributor seeking to expand your portfolio, or a pharmaceutical company securing your API supply chain, the intelligence contained in this report is designed to de-risk your decisions.
The full depth of this analysis—including specific regional revenue figures, precise segmentation percentages, and granular competitor benchmarking—is available in the complete Worldwide 2-Cyanobenzyl Bromide Market research report. We invite strategic leaders to access the full document to equip their teams with the precise data needed to navigate the complexities of 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide 2-Cyanobenzyl Bromide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Vacuum Cleaner Bags Market to Reach US$3,553M by 2032, Growing at 3.2% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Evolving Filtration Landscape: Inside the 2026 Vacuum Cleaner Bags Market Research
In an era where supply chain volatility, regulatory shifts, and changing consumer preferences converge, the global vacuum cleaner bags market requires more than surface-level observation. At PW Consulting, we recognize that filtration consumables represent a strategic interface between appliance OEMs, aftermarket distributors, and end-users who increasingly demand respiratory health, allergen control, and operational efficiency. Our latest Worldwide Vacuum Cleaner Bags Market research is designed to equip executives, product planners, procurement leaders, and investment analysts with the structured intelligence needed to navigate 2026 decision cycles with confidence.
The market has reached an inflection point. Between 2020 and 2025, global revenue expanded from approximately USD 2,435 million to USD 2,850 million, reflecting a measured but resilient trajectory shaped by post-pandemic household investment, professional cleaning sector recovery, and the sustained deployment of bagged systems in commercial environments. Looking ahead, the forecast period from 2026 through 2032 projects continued expansion, with revenue anticipated to approach USD 2,893 million in 2026 and gradually progress toward higher valuation thresholds as regional adoption patterns, product innovation cycles, and distribution optimization mature. The compound annual growth rate across the forecast window is positioned at 3.2%, a figure that underscores steady underlying demand while highlighting the necessity of precise portfolio positioning, cost discipline, and channel strategy execution rather than broad-brush volume assumptions.
This research is not a static data sheet. It is an operational framework that translates macro trajectory into actionable strategy, enabling organizations to anticipate margin pressures, evaluate competitive vulnerability, and identify where value creation will be won or lost over the next seven years.
The Structural Forces Shaping 2026 Market Arithmetic
Understanding why the vacuum cleaner bags market moves the way it does requires attention to interconnected pressures that rarely appear in isolation. Our analysis maps several dynamics that will define competitive outcomes in 2026 and beyond.
- Upstream material economics now play a more visible role in cost structuring. Nonwoven polypropylene fabric, a critical input for synthetic and microfiber filtration bags, recorded a year-over-year price increase of 12% to reach approximately $1,450 per metric ton. This shift places pressure on manufacturers of synthetic-based bags and compels portfolio rebalancing between material categories, pricing architecture, and value-added filtration claims.
- Regulatory architecture continues to anchor product standards. The EU Ecodesign Directive 665/2013 mandates minimum dust pick-up and filtration efficiency for replaceable vacuum bags, reinforcing performance as a baseline expectation rather than a differentiator. Compliance is no longer optional; it is a market entry condition that shapes design cycles, testing protocols, and cross-border commercial strategy.
- Trade policy introduces asymmetry in sourcing and pricing. U.S. Section 301 tariffs impose duties of up to 25% on vacuum cleaner bags imported from China, altering landed-cost calculations for imported supplies and encouraging regional sourcing strategies, inventory repositioning, and channel-specific pricing adjustments.
- End-user technology preferences exert structural tension on bagged segments. Bagless vacuum models captured 65% of global sales in 2023, pressuring bagged segment margins and accelerating the need for filtration upgrades, system compatibility clarity, and compelling total-cost-of-ownership narratives that justify consumable replacement cycles.
- Quality and safety continuity supports market steadiness. As of Q1 2026, there are no active recalls on vacuum cleaner bags, with the last notable incident involving Hoover type Y bag delamination in 2018. This environment rewards manufacturers and aftermarket suppliers who institutionalize consistency, traceability, and transparent compatibility guidance.
These forces do not operate in parallel; they overlap, interact, and frequently demand trade-offs. The strategic question for 2026 is not whether the market will grow, but which players can convert complexity into defensible positioning.
What the Report Delivers: A Practitioner’s Roadmap
PW Consulting’s study is structured to support decision-making at multiple organizational levels. Rather than offering a single aggregated narrative, the research decomposes the market into analytically rigorous dimensions that executives can deploy directly in planning sessions, investment committees, and product reviews.
Coverage Architecture
The report maps the market across material segmentation, distribution pathways, and geographic reach. This allows clients to evaluate where growth is concentrated, where substitution risk is most pronounced, and where channel economics create durable advantage. The analysis is designed to support questions such as:
- Which material categories are being reshaped by cost structures, filtration expectations, and reusable-versus-disposable usage patterns?
- How do offline and online retail channels differ in margin profiles, assortment logic, and consumer purchase behavior for replacement bags?
- Where do regional demand patterns, appliance base composition, and channel maturity create differentiated opportunities for localized product strategy?
Strategic Applications
Beyond segmentation, the report provides context that supports practical interventions. Readers will find guidance relevant to portfolio pruning, SKU rationalization, compatibility positioning, aftermarket substitution dynamics, and supplier selection criteria. The study also connects market structure to operational considerations such as packaging evolution, product lifecycle management, and the role of performance claims in driving repeat purchase behavior.
Vacuum Cleaner Market
For organizations seeking to align commercial planning with market reality, the report serves as a reference point for scenario development, pricing strategy calibration, and competitive response planning. It is built to be revisited throughout the planning cycle rather than read once and archived.
Analytical Discipline
Our methodology emphasizes comparability, transparency, and relevance. Historical data from 2020 through 2025 is integrated with forward-looking projections through 2032, enabling trend validation and sensitivity discussion. The report maintains consistency in valuation language and forecast framing so that internal teams can discuss growth, share shifts, and channel contribution with a common vocabulary. Importantly, the research is constructed to support decisions, not merely to describe them.
Competitive Landscape: Ten Profiles, One Contested Arena
The vacuum cleaner bags market is shaped by a mix of appliance-linked manufacturers, specialty filtration producers, and aftermarket suppliers that compete on compatibility, performance claims, packaging, and channel access. The study profiles ten companies whose strategies illustrate how value is created and defended in a market where substitution risk, proprietary fittings, and filtration expectations continually reset commercial priorities.
Miele & Cie. KG represents the premium air-quality segment with its AirClean vacuum cleaner bags, engineered for high-efficiency filtration across Miele canister and upright platforms, including Type G/N, U1, and S500 series. Its October 2024 introduction of next-generation AirClean FJM Luftreiniger bags with enhanced allergen filtration for U1 models demonstrates how performance refinement can reinforce brand positioning and extend replacement-cycle relevance. SEBO America, LLC operates with a focused product logic around ET-1, ET-2, and ET-C microfiber vacuum bags optimized for SEBO commercial and residential models with S-class filtration, and its September 2024 exhibition of updated ET-C Comfort bags at the ISSA Show North America highlighted the continued importance of professional cleaning channels and trade visibility.
Electrolux Group supplies type E, EL, and S bags for Electrolux, Eureka, Zanussi, and Sanitaire bagged vacuum cleaners, reflecting the role of broad appliance portfolios in consolidating replacement demand across multiple brands and end-use settings. Nilfisk Group manufactures GM and RFM series bags for Nilfisk professional canister and upright vacuums, aligning consumable supply with durable professional equipment usage. Numatic International Ltd provides NVM-1CH and Henry-specific paper bags for Henry, Hetty, and commercial bagged vacuums, and its March 2024 catalog release of eco-friendly recycled paper bags for the Henry Hoover series in new packaging illustrates how sustainability messaging and packaging updates can refresh a mature product line.
Alfred Kärcher SE & Co. KG offers fleece and paper bags for Kärcher wet/dry vacuums and canister models such as the WD and VC series, showing how consumable strategies extend across mixed equipment categories. Aerus LLC serves as the exclusive manufacturer of Mikrofek and Style 3 micron bags for Kirby bagged vacuum systems, an example of tightly controlled compatibility that can support loyalty but also concentrates dependence on a single platform. EnviroCare operates as an aftermarket producer of compatible vacuum bags for Miele, SEBO, Riccar, Simplicity, and Hoover models, with synthetic and paper options that position it within the substitution economy where price, availability, and compatibility clarity become decisive. Techtronic Industries (TTI) produces bags for Hoover, Dirt Devil, and Oreck bagged upright and canister vacuums under type Y and B series, linking consumable supply to a wide consumer-facing brand footprint. Riccar America supplies R bags for Riccar and Simplicity lightweight upright vacuums, reinforcing the importance of model-specific fit and targeted distribution.
Taken together, these profiles reveal a market where competitive advantage is rarely about any single attribute. It is about the combination of filtration credibility, compatibility breadth, channel strength, brand trust, and cost structure. The report examines these themes in greater depth, allowing clients to compare strategic postures without being confined to a narrow snapshot.
Market Concentration and the Implication for Strategy
The industry’s competitive structure is moderately consolidated. The combined share of the top three competitors is approximately 42.5%, while the top five reach roughly 58.8%. This distribution indicates that leading players exert meaningful influence over pricing norms, product standards, and channel expectations, while still leaving substantial room for specialized and aftermarket participants to compete on fit, service, and cost.
For 2026 planning, this concentration pattern carries several implications. Incumbents must protect performance perception and distribution relationships while managing input cost volatility and substitution pressure from bagless alternatives. Challengers and compatible-supply entrants need to navigate fit assurance, compatibility communication, and channel access carefully, especially where tariff exposure and material cost trajectories can compress margin tolerance. OEMs and private-label strategists, meanwhile, benefit from understanding where brand equity, proprietary fittings, and filtration claims create durable retention versus where price-driven switching becomes more likely.
Why This Research Matters for 2026 Decisions
The most valuable insights in a market study are not always the ones that are easiest to publish in a summary. In a market influenced by material inflation, trade policy, regulatory baselines, channel evolution, and technology substitution, strategic advantage comes from knowing where to focus, what to test, and which assumptions deserve challenge. PW Consulting’s Worldwide Vacuum Cleaner Bags Market research is built for exactly that purpose.
Worldwide Vacuum Cleaner Bags Market
It gives leadership teams a structured view of where revenue is flowing, how product categories are differentiating, how distribution pathways are shaping purchase behavior, and how competitive positioning is likely to evolve. It helps procurement teams frame sourcing decisions in light of material trends and tariff exposure. It helps product and brand teams assess where filtration claims, compatibility clarity, and packaging updates can support repeat purchase behavior. It helps investors and analysts interpret growth potential without mistaking headline momentum for durable advantage.
Next Steps
The vacuum cleaner bags market will continue to reward organizations that combine operational discipline with strategic clarity. The full report provides the detailed segmentation evidence, competitive context, and forward-looking interpretation needed to turn that discipline into practical action. For teams preparing 2026 planning cycles, the complete analysis offers a more granular foundation for scenario modeling, portfolio review, and channel strategy. To access the full market intelligence, segmentation detail, and company-level interpretation, refer to the complete PW Consulting Worldwide Vacuum Cleaner Bags Market research and use it as a working document for cross-functional decision-making throughout the year.
For detailed analysis of this topic, please visit the official page: Worldwide Vacuum Cleaner Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Vaccine Transport Box Market Hits $745.5M in 2025, Set to Reach $1,139.59M by 2032
By pmarketresearch, 2026-09-16
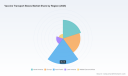
Navigating the Cold Chain: Strategic Intelligence Behind the Global Vaccine Transport Boxes Market Outlook (2026–2032)
The reliability of immunization supply chains hinges on a single, often underestimated piece of hardware: the vaccine transport box. As global health programs accelerate toward broader coverage, climate-resilient logistics, and next-generation vaccine portfolios, the demand for WHO-compliant thermal protection solutions has evolved from a procurement checklist item into a strategic infrastructure priority. The Worldwide Vaccine Transport Boxes Market research released by PW Consulting provides a comprehensive, data-grounded roadmap for executives navigating this critical cold chain segment through the forecast period ending in 2032.
This report is designed for senior decision-makers in medical device manufacturing, public health procurement, logistics contracting, and investment allocation. It translates historical trajectory, regulatory mandates, and competitive positioning into actionable intelligence. Rather than presenting static tables, the analysis weaves market sizing, structural segmentation, and firm-level profiles into a cohesive narrative that answers the questions procurement leaders and strategy officers are actually asking: Where is demand structurally shifting? Which technological pathways will dominate procurement specifications? How concentrated is the supplier base, and where do partnership or acquisition opportunities lie?
Market Trajectory and the Strategic Signal Behind the Numbers
Drawing on a historical window from 2020 through a 2025 base year, and extending forward to 2032, the research maps a market that has demonstrated resilience through periods of supply chain disruption, procurement realignments, and shifting immunization priorities. The overall market size, expressed in USD million, reflects steady commercial activity across both routine immunization programs and emergency response deployments. The trajectory from 2020 through the base year lays a foundation of established procurement cycles, while the forecast window to 2032 projects continued expansion, underpinned by a compound annual growth rate of 6.25 percent.
For executives, the strategic value of this trajectory is not in reading a single headline figure but in understanding the shape of the curve. The market has moved beyond early-stage adoption behavior into a phase where scale, specification compliance, and operational reliability define competitive advantage. Growth is being driven by the compounding effect of routine immunization catch-up, expanded cold chain footprints in emerging markets, and the operational need to reduce temperature excursions that can compromise vaccine potency. Simultaneously, the forecast period captures an inflection point in procurement behavior: buyers are increasingly prioritizing total cost of ownership, cold life reliability under extreme ambient conditions, and supplier track records rather than unit price alone.
The forecasting methodology embedded in this study stresses scenario-aware interpretation. Executives using the report are guided to evaluate base-case demand, sensitivity around procurement cycle timing, and the impact of regulation-driven specification changes. This approach matters because vaccine transport equipment is rarely a discretionary purchase; it is embedded in multi-year supply agreements, donor-funded tenders, and national immunization program calendars. Strategic planning therefore requires visibility into how demand aggregates across use cases, how replacement cycles interact with new program expansions, and how regulatory timing influences specification lock-ins.
The WHO PQS Imperative: Regulation as a Market Architecture
A defining feature of the vaccine transport boxes market is the centrality of quality and safety specification compliance. Equipment intended for procurement by UN agencies and many national programs must meet WHO Performance, Quality and Safety (PQS) requirements under the E004 category. This regulatory framework is not a peripheral certification issue; it is a structural gate that shapes supplier eligibility, procurement shortlists, and product roadmaps.
Within this framework, prequalified cold boxes and vaccine carriers are expected to demonstrate specified cold life performance at elevated ambient temperatures, including conditions reaching +43°C, while certain models must also incorporate freeze-preventive design features. These performance expectations translate directly into engineering priorities: insulation efficiency, coolant pack compatibility, sealing integrity, and ergonomic usability for field immunization teams. For businesses, the compliance layer influences everything from material selection to production QA, from documentation readiness to post-market surveillance capabilities.
The report treats regulation not as a static backdrop but as a dynamic force that interacts with procurement cycles and product innovation. For manufacturers, the strategic question is how to align R&D and production capacity with procurement calendars that increasingly require demonstrable PQS alignment early in the bidding process. For buyers and intermediaries, the strategic question is how to evaluate supplier claims against specification realities, especially when different capacity classes and transport ranges impose different cold life expectations.
Segmentation Logic That Matters for Decision-Making
The market analysis is structured around three operational segmentation lenses: region, material, and cooling technology. Each lens answers a different strategic question, and the report deliberately avoids reducing these dimensions to isolated percentage snapshots. Instead, it examines how they interact to shape procurement behavior, supplier positioning, and investment priorities.
From a regional perspective, the research maps demand geography not simply as a distribution of current sales but as a reflection of immunization program maturity, procurement channel structure, and logistical challenge profiles. Different regions present different combinations of ambient temperature stress, infrastructure availability, fleet turnover patterns, and donor funding mechanisms. Understanding these differences is essential for companies planning production allocation, service coverage, and tender participation strategies.
The material dimension addresses the core engineering tradeoff in transport box construction. High-Density Polyethylene, Polypropylene, and Polystyrene each carry distinct implications for durability, weight, manufacturing economics, and field performance. The report situates these material choices within procurement requirements, replacement cycles, and total cost of ownership considerations rather than treating them as abstract product categories. This matters because material decisions influence not only upfront pricing but also longevity, cleanability, drop resistance, and compatibility with coolant packs and handling environments.
Vaccine Refrigerators Market
Cooling technology segmentation separates passive and active cooling systems, a distinction that has operational and financial consequences. Passive systems remain central to many immunization transport scenarios because of their simplicity, independence from external power sources, and suitability for short-to-medium range logistics. Active systems introduce different performance profiles, maintenance considerations, and application boundaries. The analysis evaluates how these technology pathways are positioned across use cases, and where procurement specifications are likely to favor one approach over another based on transport distance, ambient exposure, and program design.
An important segment detail referenced in the study concerns capacity architecture. Vaccine carriers typically occupy a smaller capacity range suitable for short-range movement, while cold boxes extend toward substantially higher capacities for longer-distance transport and broader program use. This capacity continuum shapes product line strategy, tender positioning, and inventory planning. Rather than presenting rigid splits, the research uses this architecture to explain how manufacturers configure portfolios and how procurement programs match equipment classes to operational realities.
Worldwide Vaccine Transport Boxes Market
Competitive Landscape: Concentration, Positioning, and Strategic Entry Points
The supplier landscape is examined through the lens of concentration and differentiated capability. The market is not a commodity arena; it is a specification-driven environment where WHO PQS alignment, proven cold life performance, and program-level track record determine access to major procurement channels. The study reports a meaningful concentration profile, with the top three firms accounting for a significant share of market activity and the top five further consolidating a substantial portion of the competitive space. This concentration signals that scale, compliance readiness, and established procurement relationships create durable barriers for undifferentiated entrants.
At the same time, the competitive set is geographically diverse, reflecting the global nature of immunization supply chains and the distributed manufacturing base that serves them. The report profiles leading organizations across multiple regions, including established players with broad WHO PQS-prequalified portfolios and capacity ranges spanning from small carriers to larger cold boxes. These profiles emphasize product line breadth, capacity coverage, cold life orientation, and design focus areas such as freeze prevention and extended cold life performance. Several profiled firms are noted for developing series-based portfolios with capacities suited to different immunization transport scenarios, from small-volume carriers to higher-capacity cold boxes used in outreach and longer-distance logistics.
The competitive analysis is not a directory; it is a positioning map. Executives can use it to understand who competes on specification breadth, who competes on production reliability, who competes on program-level familiarity, and where there may be white space for targeted product development or partnership. The study also highlights how firms differentiate through series architecture, capacity coverage, and design priorities aligned to field conditions. For procurement teams, these profiles help frame supplier evaluation beyond catalog listings. For investors and corporate strategy groups, they illuminate where consolidation, capability acquisition, or geographic expansion may create value.
Because the market interfaces with UN agency procurement and national program sourcing, competitive advantage often depends on readiness to meet recurring tender specifications and on the operational capability to sustain supply consistency. The report explores how incumbents maintain relevance through compliance continuity, portfolio refresh, and responsiveness to procurement design changes. It also addresses the practical reality that market concentration does not eliminate opportunity; it changes the shape of it. New entrants and expanding players typically succeed by targeting specific capacity classes, improving cold life performance within defined ambient parameters, or strengthening regional service and supply reliability rather than attempting undifferentiated broad-market competition.
What the Report Delivers: Operational Content for Execution
To convert strategic context into execution, the research is built around a practical content architecture designed for cross-functional use. The report does not limit itself to market sizing; it integrates structural analysis with decision-ready detail. Core content includes an examination of market dynamics shaped by regulatory requirements, procurement design, and program-level logistics needs; a segmentation discussion that interprets demand across region, material, and cooling technology; and a competitive landscape that maps firm positioning, portfolio architecture, and concentration patterns.
The study also provides an explicit view of the base year and historical years, allowing readers to benchmark recent performance before moving into the forecast horizon. The forward-looking section extends through 2032, enabling planners to align product roadmaps, capacity investments, and procurement strategies with a multi-year outlook rather than a single-year estimate. Throughout, the analysis emphasizes interpretation over enumeration, helping readers understand why demand behaves as it does and where strategic leverage can be applied.
This format is intentionally designed for use by product leaders evaluating specification priorities, operations managers planning supply reliability, procurement professionals assessing supplier readiness, and executive teams allocating capital. The objective is to provide a single coherent reference point that links market structure, compliance reality, and competitive behavior into one decision framework.
Strategic Relevance for 2026 Decision-Making
As organizations enter 2026 planning cycles, the vaccine transport boxes market presents a clear strategic message: compliance and performance reliability are no longer sufficient as standalone selling points; they are the entrance ticket. Differentiation now emerges from how well suppliers align their portfolios with procurement specifications, how credibly they demonstrate cold life performance under challenging ambient conditions, and how effectively they support the operational rhythm of immunization supply chains.
For manufacturers, the strategic priority is to ensure that product development, production readiness, and documentation capability move in lockstep with procurement calendars and PQS expectations. For logistics and program partners, the priority is to evaluate equipment choices against transport distance, ambient exposure, replacement frequency, and total operating cost. For investors, the priority is to assess where concentration creates resilience, where supplier diversification is genuinely needed, and where specification-aligned innovation can command durable demand.
The PW Consulting Worldwide Vaccine Transport Boxes Market research is structured to support these decisions with depth, discipline, and commercial relevance. It provides the macro trajectory, segmentation logic, regulatory context, and competitive landscape necessary to move from aware to actionable. To access the full dataset, detailed company profiles, forecast tables, and the complete interpretive analysis that underpin this executive overview, readers are invited to consult the complete market research report.
For detailed analysis of this topic, please visit the official page: Worldwide Vaccine Transport Boxes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Liquid Nitrogen Cryotherapy Equipment Market Hits $342.5M in 2025, 7.51% CAGR
By pmarketresearch, 2026-09-16
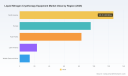
Strategic Intelligence for the Liquid Nitrogen Cryotherapy Equipment Market: Navigating the 2026–2032 Growth Trajectory
The global landscape for liquid nitrogen cryotherapy equipment is undergoing a structural transformation. As healthcare providers, medtech investors, and strategic planners confront an increasingly complex regulatory and reimbursement environment, the ability to separate short-term market noise from durable growth signals has become a critical competitive advantage. Our newly released Worldwide Liquid Nitrogen Cryotherapy Equipment Market study delivers precisely that clarity: a rigorously validated, forward-looking intelligence framework built to inform capital allocation, product positioning, and portfolio strategy across the 2026–2032 forecast horizon.
Cryotherapy Units Market
This introductory analysis outlines the strategic architecture of the research, demonstrates how the underlying data maps to real-world decision cycles, and highlights the operational and competitive dimensions that matter most to executives planning their next three to five years of growth. The narrative that follows is deliberately high-level, designed to establish analytical credibility while preserving the granular segmentation, pricing benchmarks, and regional breakdowns that await in the full report.
Why 2026 Marks a Strategic Inflection Point
Cryotherapy has evolved from a niche dermatologic intervention into a diversified therapeutic modality spanning oncology, beauty and wellness, and localized tissue management. The market’s maturation is reflected in a clear upward trajectory: from a base of approximately 342.5 million USD in 2025, the sector expands to roughly 368.67 million USD in 2026 and continues climbing through the end of the decade, with long-range projections indicating sustained momentum beyond 2030. This growth is not merely incremental; it is being shaped by an accelerating pipeline of device clearances, evolving clinical indications, and a competitive field that is actively refining capital equipment design, nitrogen-handling integration, and workflow ergonomics.
For enterprises making 2026 commitments, the question is no longer whether cryotherapy equipment will grow, but how that growth distributes across device architectures, application pathways, and geographic demand centers. Strategic planning requires a precise understanding of the operational levers that convert clinical adoption into recurring revenue, service contracts, training ecosystems, and localized supply partnerships. The full report translates these dynamics into actionable matrices, enabling stakeholders to evaluate entry timing, capacity planning, and partnership structures without relying on generic market narratives.
The Analytical Architecture of the Research
Our market study was constructed with a decision-first methodology. Rather than presenting a static snapshot of historical volumes, the analysis embeds time-series validation, competitive benchmarking, regulatory mapping, and application-specific adoption patterns into a single, referenceable intelligence system. The objective is to give strategy, commercial, and clinical affairs teams a shared factual baseline that supports scenario planning, investment committee discussions, and product roadmap alignment.
Worldwide Liquid Nitrogen Cryotherapy Equipment Market
The report addresses the full equipment value chain: capital devices used in clinical dermatology, cryoablation platforms deployed in oncology workflows, and whole-body or localized chambers positioned within wellness and recovery environments. It also examines the operational realities that determine commercial success, including nitrogen handling requirements, device durability, service infrastructure, and the increasingly important interplay between clearance status and procurement eligibility. Each section is designed for immediate reuse in internal briefing materials, partner evaluations, and market-entry modeling.
Segment Landscape Without Losing Sight of Strategy
The equipment continuum is anchored by device categories that serve distinct clinical and commercial missions. At one end of the spectrum are compact, point-of-care spray and contact instruments designed for precise lesion management in outpatient and office-based settings. These systems have become standard durable equipment in dermatology practices because they combine repeatable performance, straightforward workflow integration, and compatibility with routine cryosurgical protocols. At another tier sit more complex surgical and ablation platforms, which are increasingly evaluated not only on technical capability but also on clearance pathways, surgeon adoption patterns, and reimbursement clarity. A third category comprises chambers and localized delivery systems, which are expanding beyond traditional clinical use into recovery, rehabilitation, and consumer-adjacent wellness environments.
What makes this segmentation commercially meaningful is the divergence in adoption drivers. Clinical dermatology equipment often scales through practitioner familiarity, disposables and service ecosystems, and institutional procurement cycles. Oncology-focused platforms depend on clinical evidence generation, regulatory authorization trajectories, and integration into procedural pathways. Wellness-oriented installations frequently hinge on operational economics, site readiness, and the credibility of supplier support. The complete research quantifies these dynamics in a structured framework so that readers can compare segment economics, demand elasticity, and competitive intensity without treating the categories as interchangeable.
Geography as a Strategic Variable
Hardware strategy cannot be decoupled from regional context. Procurement norms, regulatory classification expectations, service density, and local nitrogen supply arrangements vary substantially across markets, creating different barriers to entry and different pathways to scale. A consolidated view of regional distribution highlights where installed-base momentum is strongest and where latent demand remains underpenetrated relative to clinical need and capital availability.
Rather than treating geography as a simple volume map, the report contrasts regions by procurement behavior, device mix preferences, and competitive presence. This allows readers to assess where a handheld or chamber-based offering is likely to encounter immediate traction versus where a longer commercialization timeline may be required. The detailed regional breakdowns, including market size distributions and demand concentration metrics, are reserved for the downloadable research, where they are presented alongside purchasing cycle analysis and channel considerations.
Competitive Landscape and the Meaning of Focus
The competitive field in liquid nitrogen cryotherapy equipment is shaped by manufacturers with differentiated engineering heritage, distinct clearance portfolios, and varying degrees of integration between device performance and operational support. Several established players anchor the dermatology and point-of-care segment through long-standing presence in handheld spray systems and lesion treatment workflows. Their product lines reflect decades of refinement in temperature delivery, nitrogen capacity, and clinic-friendly ergonomics, and they continue to influence procurement expectations in outpatient settings worldwide.
Adjacent to these clinical-grade spray devices are manufacturers expanding the cryosauna and whole-body chamber category, often with an emphasis on certified manufacturing environments, medical device classification alignment, and structured support for site installation and nitrogen supply integration. These producers differentiate not only through chamber design and environmental control, but also through how they position their equipment within wellness operators, recovery centers, and specialized clinical programs.
A third competitive vector is emerging around targeted cryoablation and localized destruction platforms. Recent regulatory milestones have brought liquid nitrogen cryoablation into more defined therapeutic conversations, with authorization pathways that explicitly frame the technology around specific patient populations and lesion types. For investors and OEM strategists, the significance lies less in any single clearance and more in the pattern they reveal: regulatory progress is enabling modalities once confined to narrowly defined use cases to enter broader procedural discussions, provided evidence, labeling, and reimbursement alignment evolve in parallel.
Recent product and regulatory activity reinforces this competitive maturation. Sector participants continue to refine device usability, for example through design updates that address maintenance concerns such as filter longevity and nitrogen flow consistency. At the same time, multiple entities have advanced through U.S. clearance processes for cryosurgical and ablation-related indications, signaling that the pipeline remains active and that market access conditions are being incrementally reshaped. These developments matter because procurement teams increasingly weigh not just technical capability, but the durability of regulatory standing, post-market obligations, and supplier reliability over the equipment lifecycle.
Regulatory and Reimbursement Dynamics as Decision Inputs
One of the most actionable contributions of the study is its treatment of regulatory and reimbursement context as a planning variable rather than a background condition. Cryotherapy equipment does not sell into a uniform compliance environment. Classification expectations, quality-system alignment, and clearance pathways differ across jurisdictions and across device categories, and these differences influence procurement eligibility, clinical adoption, and risk exposure for both buyers and manufacturers.
The research maps these considerations across device types and application contexts, drawing attention to the operational implications of meeting Class II cryosurgical expectations for dermatology-focused instruments and aligning product documentation with evolving medical device frameworks in other regions. For OEMs, this landscape shapes design control, labeling strategy, and post-market surveillance planning. For distributors and clinical buyers, it affects supplier qualification, service expectations, and long-term equipment viability. By consolidating these factors into a structured view, the report helps decision-makers anticipate friction points before they become commercial obstacles.
Reimbursement, Procurement, and Commercial Readiness
Even where clinical utility is well established, commercial velocity is often determined by procurement classification, coding clarity, and the practical ease with which a facility can justify acquisition. Cryosurgical equipment used for lesion management typically operates within familiar regulatory controls, but the commercial reality of budget cycles, capital planning, and multi-stakeholder approval still dictates purchase timing and volume. For more procedure-oriented platforms, reimbursement narratives and clinical pathway integration become central to adoption, meaning that product roadmaps must be synchronized with evidence generation, labeling scope, and the pace at which payers and providers incorporate new indications into standard workflows.
The report translates these considerations into commercial readiness themes: what kind of documentation and service infrastructure supports acquisition confidence, how installation and nitrogen supply partnerships influence site-level economics, and where the opportunity lies in bundling devices with training, maintenance, and operational support. These elements are especially relevant for enterprises evaluating expansion into adjacent geographies or application verticals where local credibility can be as important as product performance.
How Strategic Leaders Should Use This Intelligence
The value of the report lies in its portability across decision contexts. For corporate strategy teams, the analysis supports market-entry timing, segment prioritization, and resource allocation by connecting demand signals with competitive intensity and regulatory exposure. For product leaders, it provides an evidence-based frame for assessing whether to deepen presence in existing device categories, introduce complementary accessories or service offerings, or prepare for additive capabilities in response to evolving clinical use. For investors and partners, it clarifies where durability of competitive advantage is likely to come from: manufacturing quality, clearance standing, installation and supply integration, clinician adoption, and post-market support, rather than headline market growth alone.
In practice, the research is built to be operationalized. Readers can align internal scenario models with validated time-series trajectories, benchmark product positioning against established manufacturers and recent entrants, evaluate the implications of regulatory developments on commercial timelines, and identify geographic or application spaces where purchasing behavior and device mix create asymmetric opportunities. This is intelligence designed for use, not merely inspection.
What the Full Report Delivers
This article is a strategic preview. The complete Worldwide Liquid Nitrogen Cryotherapy Equipment Market research goes further, offering a detailed quantitative foundation and a structured qualitative backdrop calibrated for executive decision-making. It integrates validated market sizing and growth projections across the base year and forecast window, examines segmentation dynamics across equipment types and application pathways, and provides consolidated regional distribution perspectives that illuminate where demand is concentrated and how competitive presence varies by market.
Beyond macro data, the report delivers buyer-facing commercial intelligence: competitive profiles that connect product heritage with clearance status, recent regulatory and product developments that affect market access, manufacturing quality and classification context where relevant, and the operational variables that determine whether equipment translates into sustainable revenue. The objective is to give leadership teams a single, defensible reference point for planning through 2032.
Begin the Decision with the Right Map
Liquid nitrogen cryotherapy equipment sits at the intersection of clinical utility, regulatory evolution, and expanding application breadth. Growth is real, but where value will be captured in 2026 and beyond depends on how precisely organizations understand device differentiation, regional demand behavior, clearance trajectories, and the operational infrastructure that turns a promising modality into a profitable, scalable business. Our report provides that understanding in a form built for strategy, procurement, and investment teams alike.
For decision-makers who need the full segmentation detail, regional breakdowns, competitor positioning, and the complete forecast series to support planning, the comprehensive report is available through our market intelligence portal. Access it directly to move from strategic overview to actionable intelligence and to ensure your next planning cycle is grounded in validated market structure rather than partial signals.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Nitrogen Cryotherapy Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oral Solid Dosage Medicine Market to Reach $1.13 Trillion by 2032, 6.3% CAGR
By pmarketresearch, 2026-09-16
Global Oral Solid Dosage Medicine Market: Strategic Outlook 2026-2032
The worldwide oral solid dosage (OSD) medicine market stands at a critical inflection point as the industry transitions from historical growth patterns into a new cycle defined by manufacturing localization, patent cliffs, and supply chain restructuring. Our latest comprehensive study, covering the historical period from 2020 through 2025 and extending forecast projections to 2032, provides the strategic intelligence required to navigate this complex landscape. This article outlines the core dynamics shaping the sector and demonstrates why precise, forward-looking market intelligence is indispensable for corporate decision-making in 2026.
Market Trajectory and Structural Growth Drivers
The OSD sector has demonstrated consistent expansion over the past half-decade, with global revenue climbing from approximately 546 billion USD in 2020 to an estimated 738.5 billion USD in 2025. This trajectory reflects not only baseline pharmaceutical demand but also the structural advantages of solid dosage forms, which continue to dominate prescription volume due to patient compliance, manufacturing scalability, and established distribution networks. The forecast period through 2032 points toward sustained momentum, with the market projected to surpass the one trillion USD threshold before the end of the decade and approach 1.13 trillion USD by 2032. Driving this expansion is a compound annual growth rate of 6.3 percent, a figure that underscores the resilience of oral formulations even as biologic therapies and novel delivery mechanisms capture headlines.
Several macroeconomic and clinical forces reinforce this growth profile. Aging demographics across developed and emerging markets continue to elevate prevalence rates for chronic conditions that rely heavily on long-term oral therapy regimens. Simultaneously, healthcare systems worldwide are prioritizing cost containment, which paradoxically benefits OSD products given their established manufacturing efficiencies and the substantial share of prescriptions filled by lower-cost generic alternatives. The interplay between volume expansion and pricing pressure creates a nuanced environment where manufacturers must optimize production throughput, reduce waste, and invest in advanced formulation technologies to maintain margin integrity.
Segmentation Landscapes: Dosage Forms and Therapeutic Areas
Understanding where value concentrates within the OSD ecosystem is essential for portfolio strategy and capacity planning. Tablets remain the dominant dosage form, commanding the largest share of global revenue among solid oral formats, followed by capsules which serve distinct patient populations and drug stability requirements. Powders, granules, and other solid forms occupy more specialized niches, often tied to pediatric formulations, compounding scenarios, or specific regional distribution channels. The relative weighting of these formats shapes capital expenditure decisions, as firms evaluate whether to expand existing tablet lines, invest in capsule-specific encapsulation infrastructure, or develop flexible manufacturing suites capable of handling multiple solid dose configurations.
Therapeutic area segmentation further reveals where demand intensity and innovation pipelines intersect. Chronic metabolic and diabetes-related disorders represent a substantial revenue center, reflecting the global burden of insulin resistance, type 2 diabetes, and related comorbidities. Oncology follows as a critical growth vector, with oral oncolytics increasingly complementing infusion-based regimens and enabling decentralized treatment models. Cardiovascular indications, central nervous system disorders, and infectious diseases each contribute meaningful share, while aggregate demand across other therapeutic categories rounds out the portfolio. The distribution of revenue across these areas highlights the importance of therapeutic diversification for manufacturers seeking to mitigate cyclical risks and align production capabilities with high-growth clinical segments.
Regional Dynamics and Supply Chain Realities
Geographic distribution of OSD consumption and production continues to evolve as trade policies, labor economics, and regulatory frameworks reshape manufacturing footprints. North America remains a dominant revenue region, underpinned by deep pharmaceutical infrastructure, robust clinical demand, and sustained investment in domestic production capacity. Europe maintains a substantial market position, though it faces distinct regulatory and cost pressures that influence sourcing decisions and manufacturing localization strategies. Asia Pacific represents a sizable and growing region, driven by expanding healthcare access, generic manufacturing scale, and increasing domestic consumption of finished dosage forms. Latin America and the Middle East and Africa, while smaller in absolute revenue terms, present strategic opportunities for market penetration, emerging clinical needs, and cost-competitive manufacturing hubs.
Supply chain dynamics add further complexity to regional analysis. Recent data indicate that active drug shortages in the United States declined from peak levels observed in early 2024, yet remain elevated relative to pre-pandemic baselines, creating intermittent disruptions across various OSD products. Excipient supply volatility, including notable price spikes for microcrystalline cellulose and lactose, contributed to more than a quarter of documented shortages in 2024, prompting manufacturers to pursue dual-sourcing strategies and alternative raw material qualification. Additionally, the potential imposition of tariffs on active pharmaceutical ingredients threatens to raise input costs for imported generic OSD products, a concern amplified by the fact that a significant majority of generic tablets and capsules consumed in the United States originate from overseas sources. These supply-side pressures are catalyzing a broader reevaluation of where and how solid dose products are manufactured.
Competitive Landscape and Capital Allocation Signals
The OSD market is characterized by a mix of large multinational originators, specialized generic manufacturers, and contract development and manufacturing organizations that collectively shape capacity, innovation, and pricing dynamics. Industry concentration metrics indicate a moderately fragmented landscape, with the top three firms accounting for a combined share in the high teens and the top five firms commanding just under a quarter of total revenue. This structure reflects both the scale advantages of global pharmaceutical enterprises and the specialized capabilities of regional and niche manufacturers that serve distinct customer segments.
Strategic capital allocation among leading participants signals where the industry is placing its long-term bets. Novartis has announced a substantial multi-year investment program in United States infrastructure, including a dedicated facility for chemical drug substances, oral solid dosage forms, and packaging, reinforcing a trend toward end-to-end domestic production for key medicines. Eli Lilly and Company has similarly committed to a major manufacturing expansion in the Netherlands, focusing on advanced oral solid dosage technologies to support a portfolio that includes next-generation cardiometabolic therapies. Piramal Pharma Solutions has moved to strengthen its fixed-dose combination capabilities through a dedicated suite partnership, while LGM Pharma continues to scale its United States presence with incremental investments targeting niche, high-value oral solid dose products and orally disintegrating tablet formats. These commitments illustrate a broader industry emphasis on securing manufacturing capacity for high-priority molecules, reducing dependency on concentrated supply nodes, and building flexibility into production networks.
The contract manufacturing segment remains equally vital, with leading CDMOs expanding their OSD development and commercial scale-up capabilities across multiple global sites. Firms specializing in high-potency compounds, complex formulation strategies, and integrated packaging solutions are positioned to benefit as innovator companies increasingly rely on external partners to manage capacity bottlenecks and accelerate time-to-market. Generic-focused manufacturers continue to play an indispensable role in ensuring broad access to oral solid therapies, particularly as patent expirations open substantial revenue pools to competitive entry.
Patent Expirations, Generics, and Pricing Realities
One of the most consequential dynamics facing the OSD market over the forecast horizon is the wave of small-molecule patent expirations projected between 2025 and 2030. Analysts estimate that these expirations could result in hundreds of billions of dollars in revenue erosion for originator companies, driven by rapid generic entry and steep sales declines within the first year of competition. This pattern reinforces the strategic importance of lifecycle management, formulation innovation, and manufacturing efficiency for both originators seeking to defend market position and generic manufacturers preparing to capture volume.
Generics, which are overwhelmingly oral solid dosage forms, already account for the overwhelming majority of prescription volume in the United States, supporting healthcare cost containment through lower pricing after patent expiry. For manufacturers, this reality creates a dual imperative: maintain competitive cost structures to thrive in generic markets while investing in differentiated capabilities that allow branded products to sustain premium positioning where clinically justified. The balance between volume-driven generic growth and value-driven branded strategies will remain a defining tension for OSD companies throughout the forecast period.
Why This Research Matters for 2026 Decision-Making
Entering 2026, pharmaceutical and life sciences executives face a matrix of interdependent decisions: where to allocate capital for manufacturing expansion, how to structure supply chains against ingredient volatility and trade uncertainty, which therapeutic segments to prioritize for capacity investment, and how to position product portfolios against impending patent cliffs. Generic market entrants require equally precise intelligence to time launches, assess competitive density, and secure sourcing arrangements that protect margin profiles. The depth and granularity of our Worldwide Oral Solid Dosage Medicine Market report are designed to address these needs directly.
The study provides a detailed historical reconstruction of market performance across the 2020 to 2025 period, establishing a credible baseline against which forecast assumptions can be evaluated. It maps revenue distribution across dosage forms, therapeutic areas, and regions, enabling stakeholders to identify concentration points, growth pockets, and structural shifts that may not be visible from top-line aggregates alone. Competitive profiles examine the strategic positioning, manufacturing footprints, and recent capital commitments of the companies shaping the marketplace, including major originators, generic specialists, and CDMOs that together define the operational fabric of the industry. Recent development timelines capture facility announcements, partnership structures, and capacity expansion moves that signal where the market is heading in the near term.
Orally Disintegrating Tablet Market
Beyond descriptive analysis, the report integrates regulatory, reimbursement, raw material, and regional context into a cohesive framework that supports scenario planning. Insights on drug shortage trends, excipient supply risks, potential tariff impacts, and patent expiration revenue exposure are woven into the analytical narrative to help leaders quantify vulnerabilities and stress-test strategic assumptions. This approach ensures that the intelligence is not merely descriptive but actionable, supporting decisions on capacity investment, sourcing diversification, therapeutic focus, and competitive positioning.
For organizations that require the full set of segmentation values, regional breakdowns, therapeutic area shares, competitive benchmarking metrics, and forecast trajectories across all modeled years, the complete report offers the detailed data architecture necessary for rigorous internal analysis and board-level presentation. The executive summary and sample sections provide a substantive preview of methodology and scope, while the full deliverable delivers the comprehensive dataset and strategic commentary required for implementation.
Conclusion: Positioning for the Next Phase of Growth
The worldwide oral solid dosage medicine market is entering a period in which historical growth patterns will be tested by supply chain reconfiguration, patent cliff dynamics, and evolving regional manufacturing strategies. The projected expansion toward more than 1.13 trillion USD by 2032, supported by a 6.3 percent compound annual growth rate, reflects enduring demand for oral therapies and the continued centrality of solid dosage forms to global pharmaceutical care. Yet realizing value in this environment demands more than confidence in the aggregate trend; it requires precise understanding of where growth is concentrated, which competitive moves are reshaping capacity, and how external pressures will influence cost structures and market access.
Worldwide Oral Solid Dosage Medicine Market
Our research is built to equip decision-makers with that understanding. By combining historical reconstruction, forward-looking forecasts, competitive intelligence, and contextual dynamics into a single integrated analysis, the study provides the strategic foundation needed to navigate 2026 with confidence. Stakeholders who ground their planning in this level of market clarity will be better positioned to allocate capital efficiently, manage supply risk, and capture growth opportunities as the OSD market moves into its next phase of evolution.
For detailed analysis of this topic, please visit the official page: Worldwide Oral Solid Dosage Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PTBBA Market to Reach $143.63M by 2032, Driven by 4.65% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global 4-tert-Butylbenzoic Acid Market: Strategic Insights for 2026 and Beyond
Executive Summary: The Imperative for Data-Driven Decision Making
The global chemical landscape is undergoing a period of recalibration, driven by shifting supply chain dynamics, evolving regulatory frameworks, and persistent demand from core polymer and specialty applications. For decision-makers operating in the intermediates and additives space, 2026 represents a pivotal inflection point. In this environment, precision intelligence is no longer optional; it is the foundation of resilient capacity planning, procurement strategy, and competitive positioning. PW Consulting's latest Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market research report delivers exactly that— a comprehensive, forward-looking analytical framework designed to translate market complexity into actionable strategy.
This report sits at the intersection of historical performance and forward trajectory. Drawing on a rigorous historical window spanning 2020 through 2025 and projecting outcomes across the 2026–2032 forecast horizon, the analysis captures both the structural consolidation of recent years and the emergent growth vectors that will define the next cycle. The overarching narrative is one of measured, sustained expansion: the market is projected to grow at a compound annual growth rate of 4.65 percent, supported by steady demand absorption across mature polymer applications and incremental pull from specialty grade requirements. Revenue is tracked in USD millions, providing a consistent valuation baseline for cross-markет benchmarking and investment modeling.
Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market
What distinguishes this study is its refusal to stop at headline growth. Instead, it dissects the operational and commercial architecture that underpins market performance—segment definitions, regional demand distribution, grade differentiation, feedstock economics, and the competitive maneuvers of incumbent and emerging players. The result is a strategic toolkit calibrated for procurement leaders, capacity planners, M&A analysts, and market entry strategists who need to navigate a market where margin preservation and supply security are increasingly intertwined.
Macro Market Architecture: Growth Trajectory and Structural Composition
The baseline market valuation establishes a clear upward slope over the analysis period. Revenue progressed from a measured base in the early 2020s, absorbed a notable acceleration during the 2022–2023 interval, and stabilized into a higher-order equilibrium by 2025. Looking ahead, the forecast arc signals consistent year-on-year expansion, with the market advancing through a series of stepwise increments that culminate in a substantially larger revenue pool by the close of the 2032 horizon.
This trajectory is not a mechanical extrapolation. It reflects the interplay of application reuse, downstream polymer demand retention, and the steady rationalization of grade specifications. The report frames this growth through three foundational segmentation lenses, each of which carries distinct commercial implications for buyers and producers alike.
Grade segmentation highlights the differentiated value pools within the market. High-purity refined grades command structural dominance in specification-sensitive applications, while industrial-grade material sustains a meaningful share tied to cost-optimized formulations and bulk processing. The split between these tiers matters because it shapes pricing architectures, contract structures, and qualification pathways—particularly for buyers who must balance performance requirements against total cost of ownership.
Application segmentation underscores the concentration of demand across a handful of core uses. A leading application category anchors a substantial portion of total consumption, supported by a secondary tier of high-volume functional additives and a broader tail of specialty and niche uses. This demand architecture has direct consequences for supply reliability, inventory strategy, and the pace at which new capacity can be absorbed without creating localized oversupply.
Regional segmentation reveals a market whose demand geography is heavily weighted toward one dominant zone, with a layered set of secondary regions contributing differentiated volumes. This distribution pattern has strategic ramifications for logistics optimization, localized inventory positioning, and the negotiation of long-term supply agreements. It also frames the relative exposure of different buyer bases to freight volatility, import dependency, and regional regulatory shifts.
Strategic Segment Intelligence: Understanding the Layers That Drive Value
For executives who require more than aggregated totals, the report delivers a granular but disciplined breakdown of the segments that constitute the total market. Rather than presenting segmented data as isolated percentages, the analysis contextualizes each layer within its commercial logic—explaining why certain grades persist in premium positioning, why specific applications exhibit resilient consumption, and how regional demand concentration influences sourcing risk.
The refined-grade segment, defined by purity thresholds exceeding 99 percent, occupies a central role in applications where impurity control, reproducibility, and downstream processing consistency are non-negotiable. Buyers in this tier typically operate under tighter qualification cycles and prioritize supplier reliability over marginal price differences. The industrial-grade segment, spanning the 98–99 percent range, serves a different commercial logic—one oriented toward volume efficiency, cost containment, and formulation flexibility. Understanding the balance between these two pools is essential for producers calibrating product mix and for buyers evaluating whether grade substitution is technically viable within their own processes.
On the application side, the analysis maps how demand concentrates around polymer stabilization, nucleating functionality, resin modification, and select personal care and specialty uses. Each application cluster carries its own demand elasticity, formulation sensitivity, and substitution risk. The leading application category continues to absorb the largest share of total consumption, but the report equally tracks the contribution of nucleating agents and alkyd resin modifiers as meaningful secondary pillars. A smaller but strategically important tail of personal care and cosmetic applications, alongside other niche uses, rounds out the demand base—offering incremental growth optionality without destabilizing the core volume profile.
Regionally, the report frames the global demand map as a hierarchy rather than a flat aggregate. A leading Asia-Pacific concentration anchors the market's volume center of gravity, while Europe, North America, and a combined rest-of-world grouping contribute differentiated demand layers. This distribution has consequences for everything from freight and inventory strategy to the relative attractiveness of localized production versus import dependency. The analysis intentionally avoids reducing regional dynamics to simple share percentages; instead, it situates them within the operational realities of sourcing, lead-time management, and regulatory exposure that actually drive procurement decisions.
Competitive Landscape and Recent Industry Developments
The PTBBA market is characterized by a mix of scale-oriented producers, specialty-grade specialists, and geographically distributed suppliers whose competitive positioning varies by region, product tier, and application focus. The report profiles a curated set of key companies whose activities collectively shape pricing behavior, supply availability, and the pace of capacity evolution.
Among the profiled participants, several Chinese manufacturers stand out for their scale orientation and vertically integrated operational models. Fareast Kingstar Chemical positions itself as a major PTBBA producer with substantial annual production capacity and a broader product footprint that includes related intermediates. Its integration of research, production, and sales, backed by ISO 9001 and ISO 14001 certification, reflects the operational discipline increasingly demanded by downstream buyers. Shanghai Ruifu Chemical similarly emphasizes high-purity material above 99.0 percent by HPLC, with capabilities spanning small to bulk quantities and custom synthesis support—an offering profile that appeals to buyers requiring specification assurance and flexible order structures.
Beyond China, the competitive field includes Japanese and Korean participants with distinct value propositions. FUSO CHEMICAL supplies PTBBA within its electronic materials portfolio, packaged for controlled handling and specification integrity across 20 kg paper bag and 500 kg big bag formats—a logistics and quality-control emphasis that differentiates it in specification-sensitive procurement contexts. Dsn Chem Co., Ltd. operates as an active export-oriented supplier, reinforcing the global reach of secondary-source options that buyers can leverage for supply diversification.
India's Vinati Organics contributes a distinct application angle, producing PTBBA used in alkyd resin stabilization and sunscreen-related formulations, with a track record of pursuing capacity expansions tied to PTBBA-related production. Additional Chinese producers, including Jiangxi Yongtong Technology, Hebei Aoge Chemical, Dalian Richfortune Chemicals, Haicheng Huacheng Chemical, and China Haohua Chemical Group, populate the broader supply base, each contributing to the market's overall availability and competitive tension across industrial and polymer-additive segments.
Recent developments further shape this competitive picture. A capacity expansion signal observed in April 2026 underscores a structural shift: reliance on imported intermediates for high-purity PTBBA is prompting investments in domestic capacity expansion, particularly across Asia. For procurement and supply-chain leaders, this signals a medium-term recalibration of import dependency, potential shifts in lead times, and the gradual emergence of new supply nodes that could alter regional negotiation dynamics.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
On the regulatory and trade front, a European Commission autonomous tariff suspension for 4-tert-butylbenzoic acid has maintained a zero-duty environment through the end of 2027. This policy posture reduces one layer of cost friction for import-dependent European buyers and reinforces the strategic relevance of import logistics and supplier qualification within the EU market context.
Feedstock Economics, Regulatory Context, and Demand Drivers
No analysis of PTBBA market dynamics is complete without addressing the upstream economics and regulatory architecture that condition supply behavior. The primary feedstock for 4-tert-Butylbenzoic Acid is p-tert-butyltoluene, produced via alkylation of toluene and subsequently oxidized to PTBBA. This linkage means that feedstock availability and pricing exert a direct influence on PTBBA production economics. Industry data points to a notable year-on-year price rise in related TBT markets, which has affected 2026 capacity utilization and reinforced the importance of feedstock hedging, supplier relationship management, and formulation flexibility.
Regulatory context adds another strategic dimension. PTBBA is registered under REACH with harmonized classification elements that include reproductive toxicity category considerations and specific hazard statements. For downstream users, this translates into documentation requirements, handling protocols, and supplier due diligence that must be factored into sourcing decisions. The regulatory landscape is also evolving in adjacent geographies: Taiwan's environmental authority included 4-tert-butylbenzoic acid in its prioritized existing chemicals batch for data collection and assessment, signaling a potential trajectory of heightened data requirements and compliance scrutiny in one more regional market.
On the EU side, historical context remains relevant for understanding current supply patterns. The absence of active EU production since around 2006 means that European demand relies on imports, with historical market volume estimates framing the scale of that import-dependent demand base. Combined with the tariff suspension environment, this creates a market structure where import reliability, supplier qualification, and logistics resilience are especially salient for European procurement teams.
These feedstock and regulatory dynamics do not merely add background color; they actively shape margin structures, supply risk profiles, and the relative attractiveness of different sourcing strategies. The report integrates these factors into its forward analysis so that buyers and producers can assess not just where demand is going, but what constraints and opportunities will condition the path to get there.
What the PW Consulting Report Delivers: Practical Tools for 2026 Strategy
Beyond market sizing and segmentation, the report is built around practical analytical deliverables that convert information into decision support. It provides a structured view of the competitive field, enabling users to map supplier capabilities, grade specializations, and regional footprints against their own procurement and expansion requirements. It frames demand by application and grade in a way that supports formulation planning, qualification prioritization, and substitution analysis. It contextualizes feedstock and regulatory factors so that supply-chain teams can incorporate them into risk assessments and sourcing models rather than treating them as peripheral considerations.
The report also addresses the operational implications of recent capacity and trade developments. By linking the observed capacity expansion signal to its underlying driver—imported intermediate reliance—and connecting the European tariff environment to its implication for import cost structures, the analysis helps users anticipate shifts rather than simply react to them. This forward orientation is particularly valuable for teams planning contract negotiations, inventory positioning, and qualification pipelines in a year when supply-side dynamics are actively evolving.
Concentration metrics further enrich the competitive picture. The market displays a meaningful degree of supplier concentration, with a defined share captured by a smaller group of leading participants. For buyers, this has implications for negotiation leverage, qualification redundancy, and the strategic value of qualifying secondary sources. For producers and investors, it highlights the commercial significance of scale, grade differentiation, and application-specific positioning as the market matures.
Why This Research Matters for 2026 Decision-Making
In a market defined by measured growth, concentrated demand, and shifting supply-side incentives, strategic advantage belongs to organizations that can align their sourcing, production, and expansion decisions with a clear-eyed view of where the market is heading. The PW Consulting Worldwide 4-tert-Butylbenzoic Acid Market report is designed to provide that view. It combines historical grounding, forward projection, segment-level intelligence, competitive profiling, and regulatory and feedstock context into a single analytical framework calibrated for executive use.
For procurement leaders, the report supports more resilient sourcing strategies by clarifying the demand layers, grade sensitivities, and supplier capabilities that actually drive supply security. For capacity planners and producers, it provides a demand trajectory and segmentation context that can inform investment timing, product-mix calibration, and regional focus. For market-entry and M&A teams, it offers the structural insight needed to evaluate where value is created, where competition is intensifying, and where white space or consolidation opportunities may emerge.
Full detail, including complete segmentation figures, regional and application-level data, and extended competitor profiles, is available in the complete study. The summary presented here is intended to demonstrate the analytical depth and strategic relevance of the research while preserving the full dataset and supporting detail for the in-depth review. Readers seeking the complete intelligence package are encouraged to access the full report to ensure that procurement, investment, and planning decisions are grounded in the complete market picture.
For detailed analysis of this topic, please visit the official page: Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cooperage Equipment Market Hits $210.5M in 2025, Projects 6.85% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Cooperage Equipment Market: Navigating the 2026 Landscape
Executive Overview
The global cooperage equipment market is undergoing a structural transformation, driven by tightening quality standards in premium winemaking, evolving spirits aging protocols, and continuous automation across production facilities. Our latest market research provides decision-makers with a rigorous, forward-looking assessment of how equipment procurement, capacity planning, and competitive positioning will evolve through 2032. For executives operating in food and beverage manufacturing, industrial packaging, or specialized barrel production, this intelligence report delivers the analytical framework needed to align capital allocation with long-term operational resilience.
Drawing on historical performance data spanning 2020 through 2025 and projecting forward across the forecast period, the study maps a clear trajectory of sustained expansion. The overall market revenue reached approximately 210.5 million USD in 2025, reflecting a compound annual growth rate of 6.85 percent projected across the forecast horizon. By 2032, the sector is positioned to surpass 336 million USD in total revenue. These figures represent more than isolated growth metrics; they signal a maturing equipment ecosystem that is increasingly defined by precision engineering, workflow integration, and selective automation. For corporate strategists, understanding where value is concentrated and how purchasing priorities are shifting will determine competitive advantage in the coming cycle.
Market Trajectory and Strategic Implications
The historical arc from 2020 to 2025 reveals a consistent upward trend, with periodic accelerations tied to capacity expansions and technology adoption cycles. Revenue climbed from 142.35 million USD in 2020 to 151.89 million USD in 2021, then to 164.46 million USD in 2022, before reaching 173.91 million USD in 2023. The pace quickened notably as manufacturers invested in modernization, pushing figures to 202.97 million USD in 2024 and stabilizing at 210.5 million USD in 2025. This progression illustrates how post-pandemic operational restructuring and sustained demand for high-quality aging containers have reinforced investment confidence.
Looking ahead, the forecast period outlines a steady climb: 228.85 million USD in 2026, followed by 252.72 million USD in 2027. A brief normalization is expected in 2028 at 251.36 million USD, after which the market resumes its expansion toward 273.85 million USD in 2029, 290.19 million USD in 2030, 302.36 million USD in 2031, and 336.32 million USD in 2032. This pattern reflects a market that is not merely growing but recalibrating around efficiency, durability, and process control. Strategists should interpret these movements as indicators of where procurement budgets will be allocated, which equipment categories will face supply constraints, and how regional production networks will respond to shifting input costs.
Category Architecture and Operational Demand
The report dissects the market through multiple lenses, beginning with equipment type. Automatic equipment currently commands the larger revenue share, reflecting a broader industry preference for integrated handling, precision toasting, and repeatable finishing workflows. Manual equipment maintains a substantial presence, particularly among smaller production houses and specialty operations that prioritize flexibility and lower upfront capital exposure. The balance between these two categories continues to evolve as labor availability, throughput expectations, and quality assurance requirements reshape purchasing criteria.
Cooperage Equipment Market
Application segmentation further clarifies how demand is distributed across end-use environments. The food and beverage sector anchors the majority of equipment consumption, driven by beverage maturation, barrel maintenance, and hygiene-focused processing requirements. Industrial applications follow as a secondary but strategically important segment, while other specialized uses contribute additional demand where customized barrel construction or niche finishing processes are required. Understanding how these application streams interact with procurement cycles, maintenance schedules, and technology upgrade paths is essential for forecasting equipment utilization and capital replacement timing.
Wine Fermentation Equipment Market
Geographic Distribution and Supply Chain Considerations
Regional dynamics play a defining role in how equipment demand materializes. Europe represents the most significant market concentration, reflecting the depth of traditional barrel craftsmanship, established winery infrastructure, and sustained investment in aging-related processing. North America follows as a major demand center, shaped by large-scale beverage production, expanding distillery operations, and ongoing facility modernization. Asia Pacific, Latin America, and the Middle East and Africa collectively add further layers of growth, with each region exhibiting distinct procurement rhythms, import dependencies, and capacity-building timelines.
For strategic planners, regional variation is not simply a geographic breakdown but a signal of where service networks, parts availability, and technical support must be positioned. Companies evaluating expansion, distributor partnerships, or localized service capabilities will find the report’s regional analysis instrumental in mapping execution risk and identifying where equipment deployment is likely to face the strongest operational pull.
Competitive Landscape and Enterprise Positioning
The market’s competitive structure remains moderately concentrated, with the top three participants accounting for approximately 38.5 percent of revenue and the top five reaching about 52.7 percent. This concentration indicates a landscape where established suppliers hold meaningful influence over product standardization, service ecosystems, and technological direction, while still leaving room for specialized players to differentiate through application expertise, regional reach, and targeted product lines.
Within this environment, several companies illustrate the breadth of strategic approaches shaping the sector. Prospero Equipment Corporation, headquartered in Windsor, California, supplies cooperage equipment including barrel washers, hoop drivers, and stave planers designed for wine and spirits producers. Its recent expansion of an updated product catalog in October 2025, featuring enhanced barrel toasting and steaming equipment lines, underscores how suppliers are aligning product portfolios with production efficiency and quality consistency.
Winequip, based in Melbourne, Australia, provides cooperage machinery such as barrel repair tools, toasting equipment, and automated barrel handling systems. Its product breadth highlights the growing importance of post-production maintenance, repair capabilities, and workflow automation in sustaining long-term equipment utilization. Vintner Vault, operating from Paso Robles, California, distributes cooperage equipment including barrel racks, washing systems, and maintenance tools tailored for commercial wineries. Its distribution-oriented model demonstrates how channel strategies continue to influence equipment accessibility and implementation speed for operating facilities.
These enterprises represent different facets of the same competitive logic: product reliability, application-specific support, and the ability to meet evolving throughput expectations. The report evaluates how such players position themselves across product lines, geographic coverage, and service intensity, giving buyers and investors a structured view of where partnerships, procurement consolidation, or competitive displacement may emerge.
Operational Pressures and Input Market Reality
Equipment strategy cannot be separated from the material environment in which it operates. In 2025, French oak stave prices increased by 12 percent year-over-year due to supply constraints from European forests. This shift directly affects barrel production economics and, by extension, the demand profile for equipment that improves yield, reduces waste, and standardizes finishing outcomes. When raw material volatility intensifies, manufacturers and distributors increasingly look to equipment investments that enhance process control, improve throughput predictability, and support more consistent aging results.
For procurement leaders, this dynamic reinforces the importance of evaluating equipment not only on purchase price but on total operational value: durability, serviceability, integration with existing line configurations, and the capacity to adapt to material variability. The study incorporates these considerations into its analytical framework, helping decision-makers weigh capital deployment against the backdrop of input cost pressure and supply chain uncertainty.
What the Research Delivers for 2026 Decision-Making
This market research is structured to support practical strategic action rather than abstract observation. It combines historical trend analysis, forward-looking projections, category-level segmentation, and competitive profiling into a single decision-support framework. Readers will gain clarity on how equipment demand is evolving across major application streams, where automation is reshaping purchasing priorities, and how leading suppliers are adjusting their portfolios in response to production and material conditions.
The report also provides guidance on evaluating procurement timing, assessing service and maintenance requirements, and interpreting regional demand signals that influence deployment strategy. By integrating market size progression, concentration patterns, and company-level developments into a coherent narrative, the study enables executives to benchmark internal plans against broader market movement and to identify where strategic investment may yield the strongest operational return.
Conclusion
The cooperage equipment market is entering a phase where growth is increasingly tied to operational precision, automation maturity, and responsiveness to material cost dynamics. With revenue projected to advance from 228.85 million USD in 2026 toward 336.32 million USD by 2032, the sector presents both opportunity and execution risk for organizations navigating equipment procurement, production scaling, and competitive positioning. This research report is designed to give strategists, purchasing leaders, and industry executives the context needed to make informed decisions with confidence. To access the complete segmentation analysis, regional breakdowns, application-level demand patterns, and full competitive profiling, visit the source page for the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Cooperage Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Antiperspirant Aluminum Chlorohydrate Market Hits $850M in 2025, Projected 5.2% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Worldwide Antiperspirant Aluminum Chlorohydrate Market: Strategic Intelligence for 2026
The global personal care industry stands at a critical juncture where formulation efficacy, regulatory compliance, and supply chain resilience intersect. For decision-makers operating within or adjacent to the antiperspirant sector, understanding the trajectory of aluminum chlorohydrate is no longer optional. As the primary active ingredient responsible for sweat reduction, aluminum chlorohydrate anchors a market that has demonstrated steady expansion through recent historical cycles and is projected to maintain disciplined growth over the coming forecast horizon. PW Consulting has compiled a comprehensive Worldwide Antiperspirant Aluminum Chlorohydrate Market study designed to translate macroeconomic signals, competitive movements, and regulatory shifts into actionable intelligence for 2026 and beyond.
This research is structured as a strategic companion rather than a static data repository. It maps historical performance across a six-year retrospective window and extends forward through a multi-year forecast period, enabling stakeholders to align procurement timelines, capacity planning, and market entry strategies with verified directional trends. The base year anchors the analysis at 2025, providing a calibrated reference point from which growth rates, concentration dynamics, and segment equilibria are measured. Readers seeking granular percentage allocations, discrete regional revenue figures, and application-specific breakdowns will find those detailed datasets within the full publication, where they are presented alongside methodological notes and scenario sensitivity models.
Market Trajectory and Macro Growth Architecture
The worldwide antiperspirant aluminum chlorohydrate market has moved from a 2023 baseline of approximately 768 million USD to an estimated 808 million USD in 2024, reaching a projected 850 million USD in 2025. This progression reflects a compound annual growth rate of roughly 5.2 percent across the forecast horizon extending through the early 2030s. Such a cadence signals a mature yet expanding category, where volume gains are increasingly intertwined with value optimization, grade differentiation, and formulation innovation rather than relying solely on population-driven demand expansion.
Forward-looking valuations trace a consistent upward slope, with the market projected to approach 894 million USD in 2026, rising to 940 million USD in 2027 and crossing the 1 billion USD threshold shortly thereafter. The trajectory culminates in a projected 1.2 billion USD valuation by the end of the forecast window. This growth architecture is underpinned by continuous refresh cycles in personal care portfolios, the proliferation of body confidence and performance-oriented grooming products, and sustained demand for reliable sweat-control actives that function across diverse climatic and cultural usage patterns.
Importantly, these headline figures represent aggregate market dynamics. The distribution of value across forms, application formats, and geographies is far from uniform. Liquid formulations continue to command a substantial share of the total value pool, while powder-based routes maintain a distinct but smaller footprint. Within application channels, roll-on and stick formats have historically anchored consumer preferences, with sprays and creams-and-other segments contributing more specialized demand profiles. Regional performance similarly reflects divergent purchasing power, climatic drivers, and regulatory environments. The complete study isolates these dimensions with precise calibration, enabling readers to benchmark their own portfolio exposure against verified segment equilibria and to identify where competitive intensity is most concentrated.
Report Content and Operational Utility for Executives
PW Consulting’s analysis is engineered for immediate operational relevance. Beyond macro valuation frames, the report delivers a structured examination of market architecture, competitive positioning, and the external forces that shape cost structures, formulation choices, and compliance pathways. The content is organized to support cross-functional alignment among procurement, R&D, regulatory affairs, and commercial strategy teams, ensuring that insights can be translated into concrete action plans without requiring additional data reconstruction.
The document includes a detailed segmentation exploration that maps how different product forms and application formats compete for consumer attention and manufacturer investment. It describes the structural factors that drive volume allocation across these categories, including textural expectations, packaging compatibility, ease of formulation, and regional usage habits. By presenting these dynamics in a comparative framework, the report helps stakeholders identify where formulation innovation can unlock incremental share and where cost optimization may be achieved through grade selection or processing adjustments.
Supply-side intelligence forms another core pillar of the publication. The research examines the upstream ecosystem that feeds aluminum chlorohydrate production, including the role of alumina feedstocks, specialty chemical processing, and purity specifications required for cosmetic and personal care applications. It contextualizes how raw material pricing movements, refinery and specialty alumina capacity decisions, and logistics cost fluctuations influence the effective cost of goods for downstream formulators. These elements are treated not as isolated news items but as integrated variables within a cost-and-supply model that can be applied to budgeting, hedging considerations, and supplier evaluation processes.
The report also incorporates a regulatory and compliance review that addresses evolving chemical safety frameworks, concentration limits, labeling requirements, and regional substance restrictions. Regulatory trajectories are analyzed for their potential to reshape formulation choices, especially in high-sensitivity markets where consumer exposure concerns intersect with product efficacy expectations. By mapping these developments alongside ingredient functionality and grade differentiation, the study equips teams to anticipate reformulation needs, assess alternative grade suitability, and maintain alignment with both current mandates and emerging precaution-based standards.
Competitive Landscape and Key Company Positioning
The antiperspirant aluminum chlorohydrate market reflects a moderately concentrated competitive environment, with a limited group of large suppliers accounting for a significant portion of total value. This concentration creates both advantages and vulnerabilities for downstream customers. On one hand, established suppliers offer consistent quality, broad grade portfolios, and the ability to support global scale demands. On the other, reliance on a narrow supplier base can amplify exposure to capacity disruptions, regional logistics friction, and price volatility in upstream inputs. Understanding where competitive leverage resides is essential for procurement strategy and risk management.
Summit Reheis operates as a leading global supplier of aluminum chlorohydrate active ingredients for antiperspirant use, offering both standard and enhanced grades that support a wide range of deodorant and antiperspirant formulations. The company’s product range, including grades such as ACH 410 and Reheis AHA, illustrates the industry trend toward differentiated actives that balance efficacy with formulation compatibility. In late 2024, Summit Reheis introduced an ultra low-irritancy grade designed for sensitive skin antiperspirants, signaling how supplier innovation is increasingly oriented toward consumer tolerance and skin-friendly performance profiles.
Rio Tinto contributes to the supply landscape through its specialty alumina division, which produces high-purity aluminum chlorohydrate materials destined for personal care manufacturers worldwide. Its involvement highlights the importance of integrated upstream capability in maintaining consistent supply. In mid 2024, the company expanded specialty alumina production capacity by 15 percent to support growing antiperspirant active demand, demonstrating how capacity decisions at the specialty materials level can ripple through the broader market and influence availability in downstream channels.
Givaudan supplies aluminum chlorohydrate-based antiperspirant actives via its personal care division, with a focus on low-odor, high-efficacy grades that serve global deodorant brands. The company’s emphasis on sensory performance and brand-aligned characteristics reflects the broader shift in which antiperspirant actives are increasingly evaluated not only on biological efficacy but also on user experience, fragrance compatibility, and application feel. Recent updates to certification and sustainability reporting underscore the growing relevance of responsible sourcing and documented compliance in supplier selection.
Worldwide Aluminum Zirconium Tetrachlorohydrex Glycine (AZAG) Market
Nippon Light Metal Holdings manufactures high-purity aluminum chlorohydrate for antiperspirant applications, with particular emphasis on cosmetic-grade specifications and export-oriented supply reaching Asia-Pacific and global markets. Its positioning demonstrates how regional manufacturing expertise and purity control can support international demand while addressing market-specific quality expectations. In parallel, Advancion Corporation provides custom aluminum chlorohydrate solutions tailored to antiperspirant formulations, including polyaluminum chloride variants optimized for sweat reduction efficacy. This custom approach indicates a segment of the market where formulation engineers require more than off-the-shelf grades and instead seek partners who can tune material characteristics to specific performance targets.
Worldwide Antiperspirant Aluminum Chlorohydrate Market
Together, these players illustrate a competitive landscape shaped by grade differentiation, purity control, formulation support, and capacity responsiveness. The full report profiles these companies and others within a comparative framework, examining their strategic moves, product introductions, capacity actions, and certification developments. By mapping these activities against market share concentration and regional supply flows, the study clarifies where competitive barriers exist and where opportunities for differentiated supplier partnerships may emerge.
Industry Dynamics: Raw Materials, Regulation, Tariffs, and Logistics
Market behavior in aluminum chlorohydrate does not evolve in isolation. It is continuously reshaped by external conditions that influence cost, compliance, and competitive access. One of the most immediate pressures in recent quarters has come from raw material dynamics. Alumina feedstock prices have experienced notable upward movement, driven by bauxite supply constraints and broader mineral commodity tightness. This shift translates directly into elevated input costs for specialty chemical producers and, ultimately, into formulation economics for antiperspirant manufacturers. The report incorporates these material cost trends as part of a wider cost-structure analysis, helping readers distinguish between temporary shocks and structural cost recalibration.
Regulatory developments add another layer of complexity. In Europe, evolving chemical safety frameworks have introduced concentration restrictions relevant to aluminum chlorohydrate in cosmetic applications. These mandates affect formulation ceilings and can influence how brands position products across sensitive and general-use categories. Alongside concentration limits, broader environmental and health-related listings in certain jurisdictions have increased scrutiny for consumer-facing products containing aluminum compounds. Although such listings do not uniformly apply across markets, they shape labeling practice, consumer perception, and risk assessment in regions where precautionary communication is becoming more prominent.
Trade policy introduces further asymmetry across geographies. Tariff measures affecting imports of aluminum chlorohydrate from specific origins have altered the cost calculus for formulators that rely on cross-border sourcing. A 25 percent tariff structure linked to designated import classifications has placed additional pressure on supply plans that previously depended on lower-cost overseas material flows. For multinational brands and regional formulators alike, this reinforces the value of diversified sourcing, near-shoring considerations, and supplier relationships that can absorb policy-induced cost shifts without disrupting supply continuity.
Logistics costs also remain a salient factor. Global ocean freight rates for chemical shipments have seen meaningful increases, adding to the landed cost burden for internationally sourced actives and intermediates. These freight dynamics intersect with production scheduling, inventory positioning, and regional distribution strategies. In a market where grade consistency and delivery reliability matter, transportation cost volatility can influence regional pricing patterns and supplier selection even when base ingredient pricing appears stable.
Strategic Decision Framework for 2026
For executives planning 2026 operations, the strategic challenge is not merely to observe growth but to interpret it within the constraints and opportunities created by formulation trends, sourcing realities, and regulatory trajectories. The aluminum chlorohydrate market’s projected expansion at a disciplined compound rate suggests that demand will continue to provide a supportive backdrop, but that growth will increasingly reward organizations capable of managing complexity rather than simply riding volume momentum.
One priority is formulation strategy. As consumer expectations evolve around sensory feel, skin compatibility, and odor management, the selection of aluminum chlorohydrate grades becomes a tactical decision with both performance and market-access implications. Teams should evaluate how specific grades align with target user profiles, regional preference patterns, and packaging systems. The report’s segmentation insights help frame these choices by revealing how different application formats and product forms compete for share and where innovation may create differentiation without compromising cost efficiency.
A second priority is sourcing resilience. Given the concentration of supply among established active ingredient producers and the influence of upstream raw material pricing, procurement strategies should weigh supplier diversification, grade flexibility, and contractual structures that reduce exposure to freight and tariff volatility. Capacity expansion announcements from major suppliers indicate that supply-side responsiveness exists, but access to that capacity depends on relationship strength, specification alignment, and regional procurement planning. The full study provides the competitive and concentration context needed to assess where reliance is justified and where contingency planning is advisable.
A third priority is regulatory foresight. Concentration limits and precautionary listings are likely to continue shaping formulation decisions, especially for brands that operate across multiple jurisdictions. Anticipating reformulation requirements, reviewing alternative grade suitability, and monitoring certification and sustainability documentation can reduce the likelihood of disruptive compliance events. Interpretation of these developments should be integrated with R&D timelines so that product roadmaps remain aligned with both current mandates and plausible future constraints.
Finally, commercial strategy should reflect the interplay between geography, form, and application. While aggregate growth provides a positive market signal, regional and format-level dynamics differ materially. Organizations that understand where value is accumulating, which formats are driven by local usage patterns, and how trade and logistics conditions affect regional accessibility will be better positioned to allocate investment and adjust portfolio exposure. The complete report disaggregates these patterns in detail, allowing readers to map them against their own footprint and competitive context.
Why the Full Study Matters
Snapshot data and aggregated growth rates provide direction, but strategic decisions require deeper calibration. The full PW Consulting Worldwide Antiperspirant Aluminum Chlorohydrate Market report delivers the precision, segmentation detail, company-specific intelligence, and contextual analysis needed to convert market signals into executable strategy. It distinguishes between historical trend confirmation and forward-looking scenario interpretation, giving readers a structured basis for planning procurement, formulation, compliance, and market development activities throughout 2026 and beyond.
The publication is designed to serve as a shared reference point across functions, ensuring that commercial, technical, and supply teams are operating from a common evidence base. Its segmentation analysis isolates the dimensions that matter most to product planning, while its competitive and dynamics assessments provide context for risk management and supplier strategy. By consolidating macroeconomic data, regulatory developments, trade conditions, and company-level activity within a single analytical framework, the report reduces the time required to assemble actionable intelligence and increases the confidence with which decisions can be made.
For organizations seeking to navigate a market defined by steady expansion, concentrated supply, evolving regulation, and shifting formulation expectations, this research offers the depth required to move beyond generalizations and toward precise strategic positioning. The aggregated market figures, growth cadence, and competitive patterns outlined here are intended to establish the strategic frame. The detailed segmentation splits, discrete regional valuations, and application-level distributions that support them are presented in full within the complete study, where they can be examined alongside methodological notes and scenario-ready analysis.
In a category where ingredient performance, regulatory readiness, and supply continuity collectively determine market access, timely and well-structured intelligence is not an accessory. It is a prerequisite for confident action. PW Consulting’s Worldwide Antiperspirant Aluminum Chlorohydrate Market study provides that foundation, enabling leaders to align 2026 decisions with verified market direction, competitive reality, and operational feasibility.
For detailed analysis of this topic, please visit the official page: Worldwide Antiperspirant Aluminum Chlorohydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com